
In this report: The US SPR release is done and Europe is slow to release sanctioned reserves. Meanwhile Saudi is under attack and almost 4% of world production is subject to a Houthi attack at any time.
Last week. Brent +2.47% (+$2.42) Open $103.15 H $105.92 L $97.06 C $104.72
Articles
Vitol chief warns of tanker shortage and risk of $200-a-barrel oil
The Art Of The Tiny Deal: Trump’s Diesel Deal With Putin Does Nothing
Crude oil prices ease, but Saudi airport strike keeps tensions high
Saudi Capital’s Airport, World’s Largest Oil Field Hit in Yemeni Strikes
European markets rattled by near miss on US diesel export ban
IEA to decide on details of diesel stocks release next week, sources say, as market confusion grows
Around 14 million barrels per day leaving Middle East, Vitol CEO says
Depleted Global Stocks Set Higher Floor Under Oil Prices
Trump: U.S. won’t attack Iran before midterms
Hurricane Isaias (2026)
Houthis claim missile strike on Riyadh airport as explosions heard in Saudi capital
Venture Global in talks to sell US LNG to Chinese buyers, Bloomberg News reports
Yemen Becomes the Islamic State’s Media Sanctuary
View
Given the risk load over the last week, we are in my view significantly underpriced on crude oil benchmarks. The Houthis have clearly exhibited they can operate with complete impunity within both Yemen and Saudi Arabia with attacks on Riyadh airport over the weekend killing 12 and injuring over 300 people. This comes on the back of significant attacks by Iran on several tankers in The Strait of Hormuz and successful attacks on gas production facilities in the Saudi Ghawar facility. Ghawar is the worlds larges onshore oil production facility, producing 3.8million bpd as of 2019. Just to drive across this facility at 80mph would take a little over 2 hours
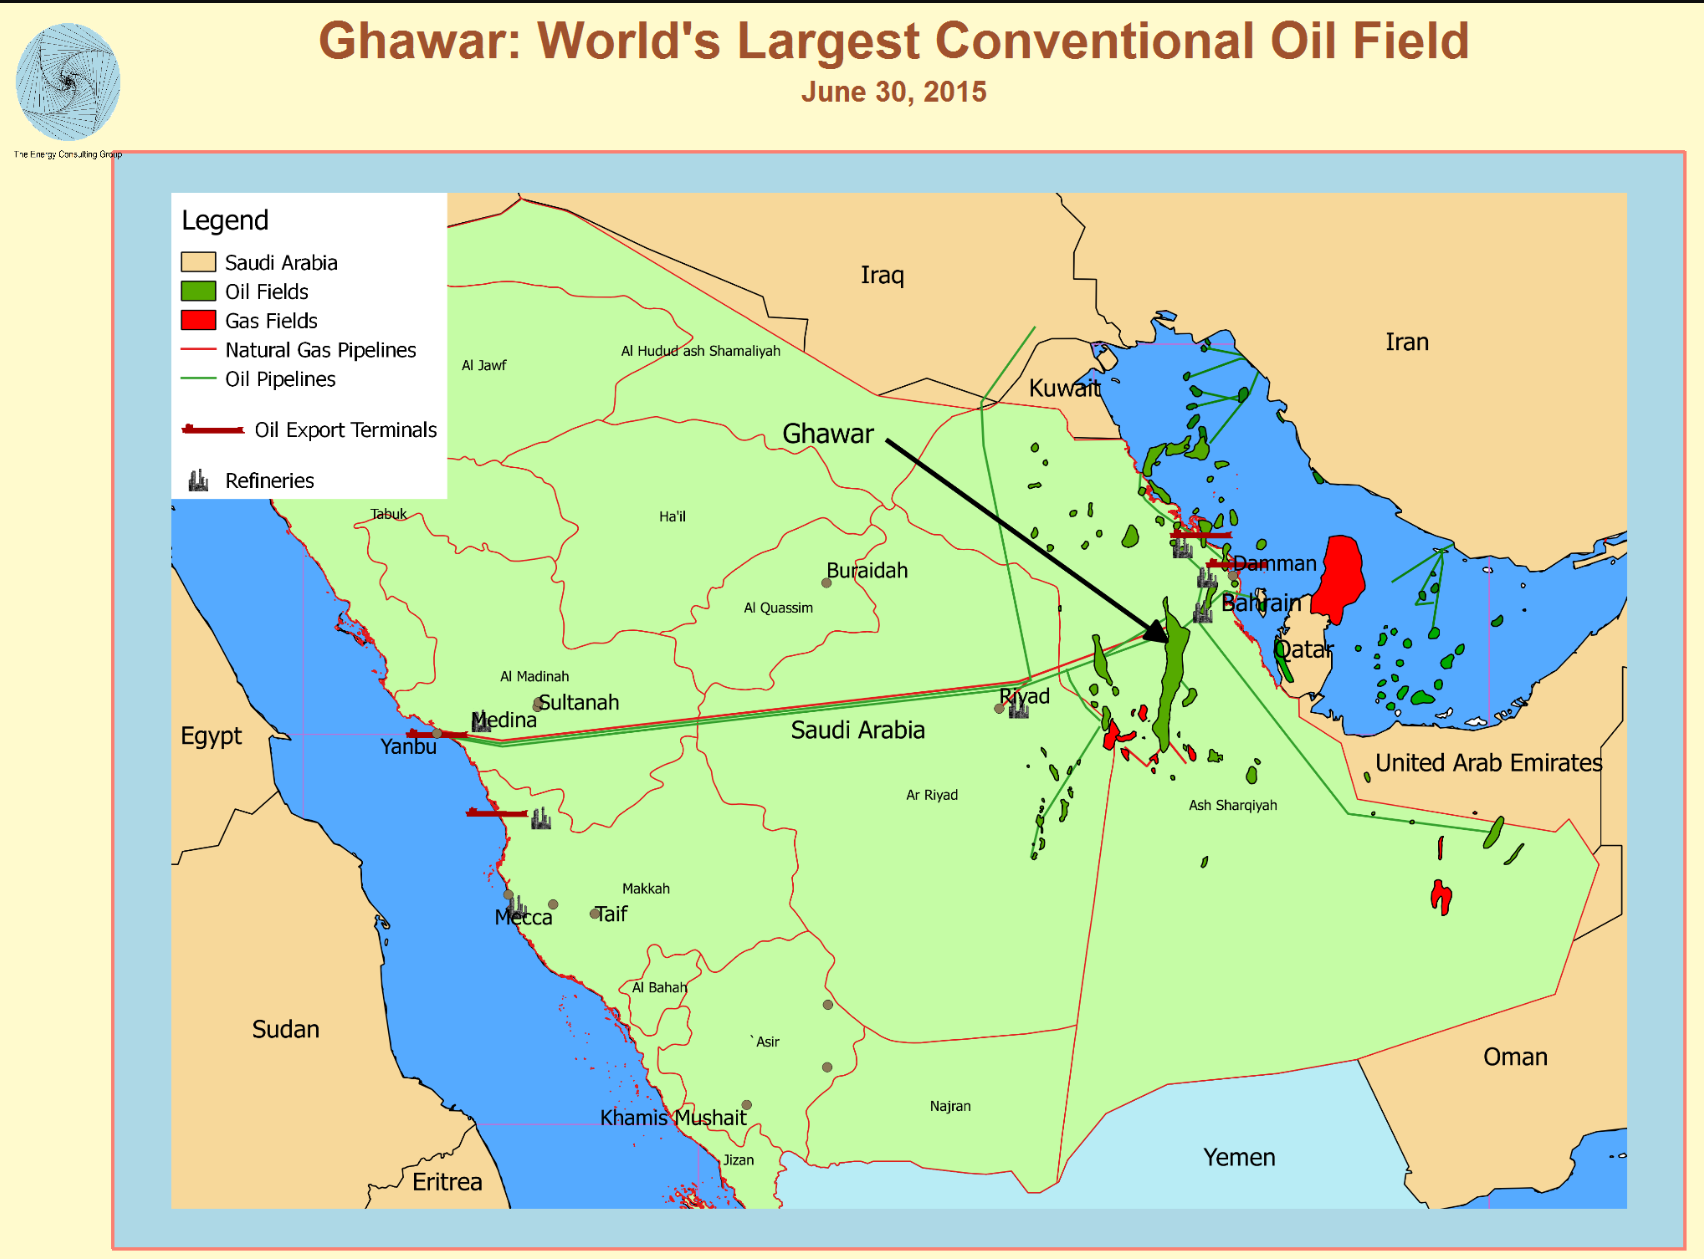
It is significant to understand this landscape if we want to be able to properly price tail risk on oil right now that is pricing in to the market as I type.
The Saudi government is aligned with the Sunni government of Yemen, while The Houthis belong to the Zaydi branch of Shia Islam. There are also pockets of Al Qaeda operating in the eastern regions of Yemen, with the Muslim brotherhood using the country as a stronghold.
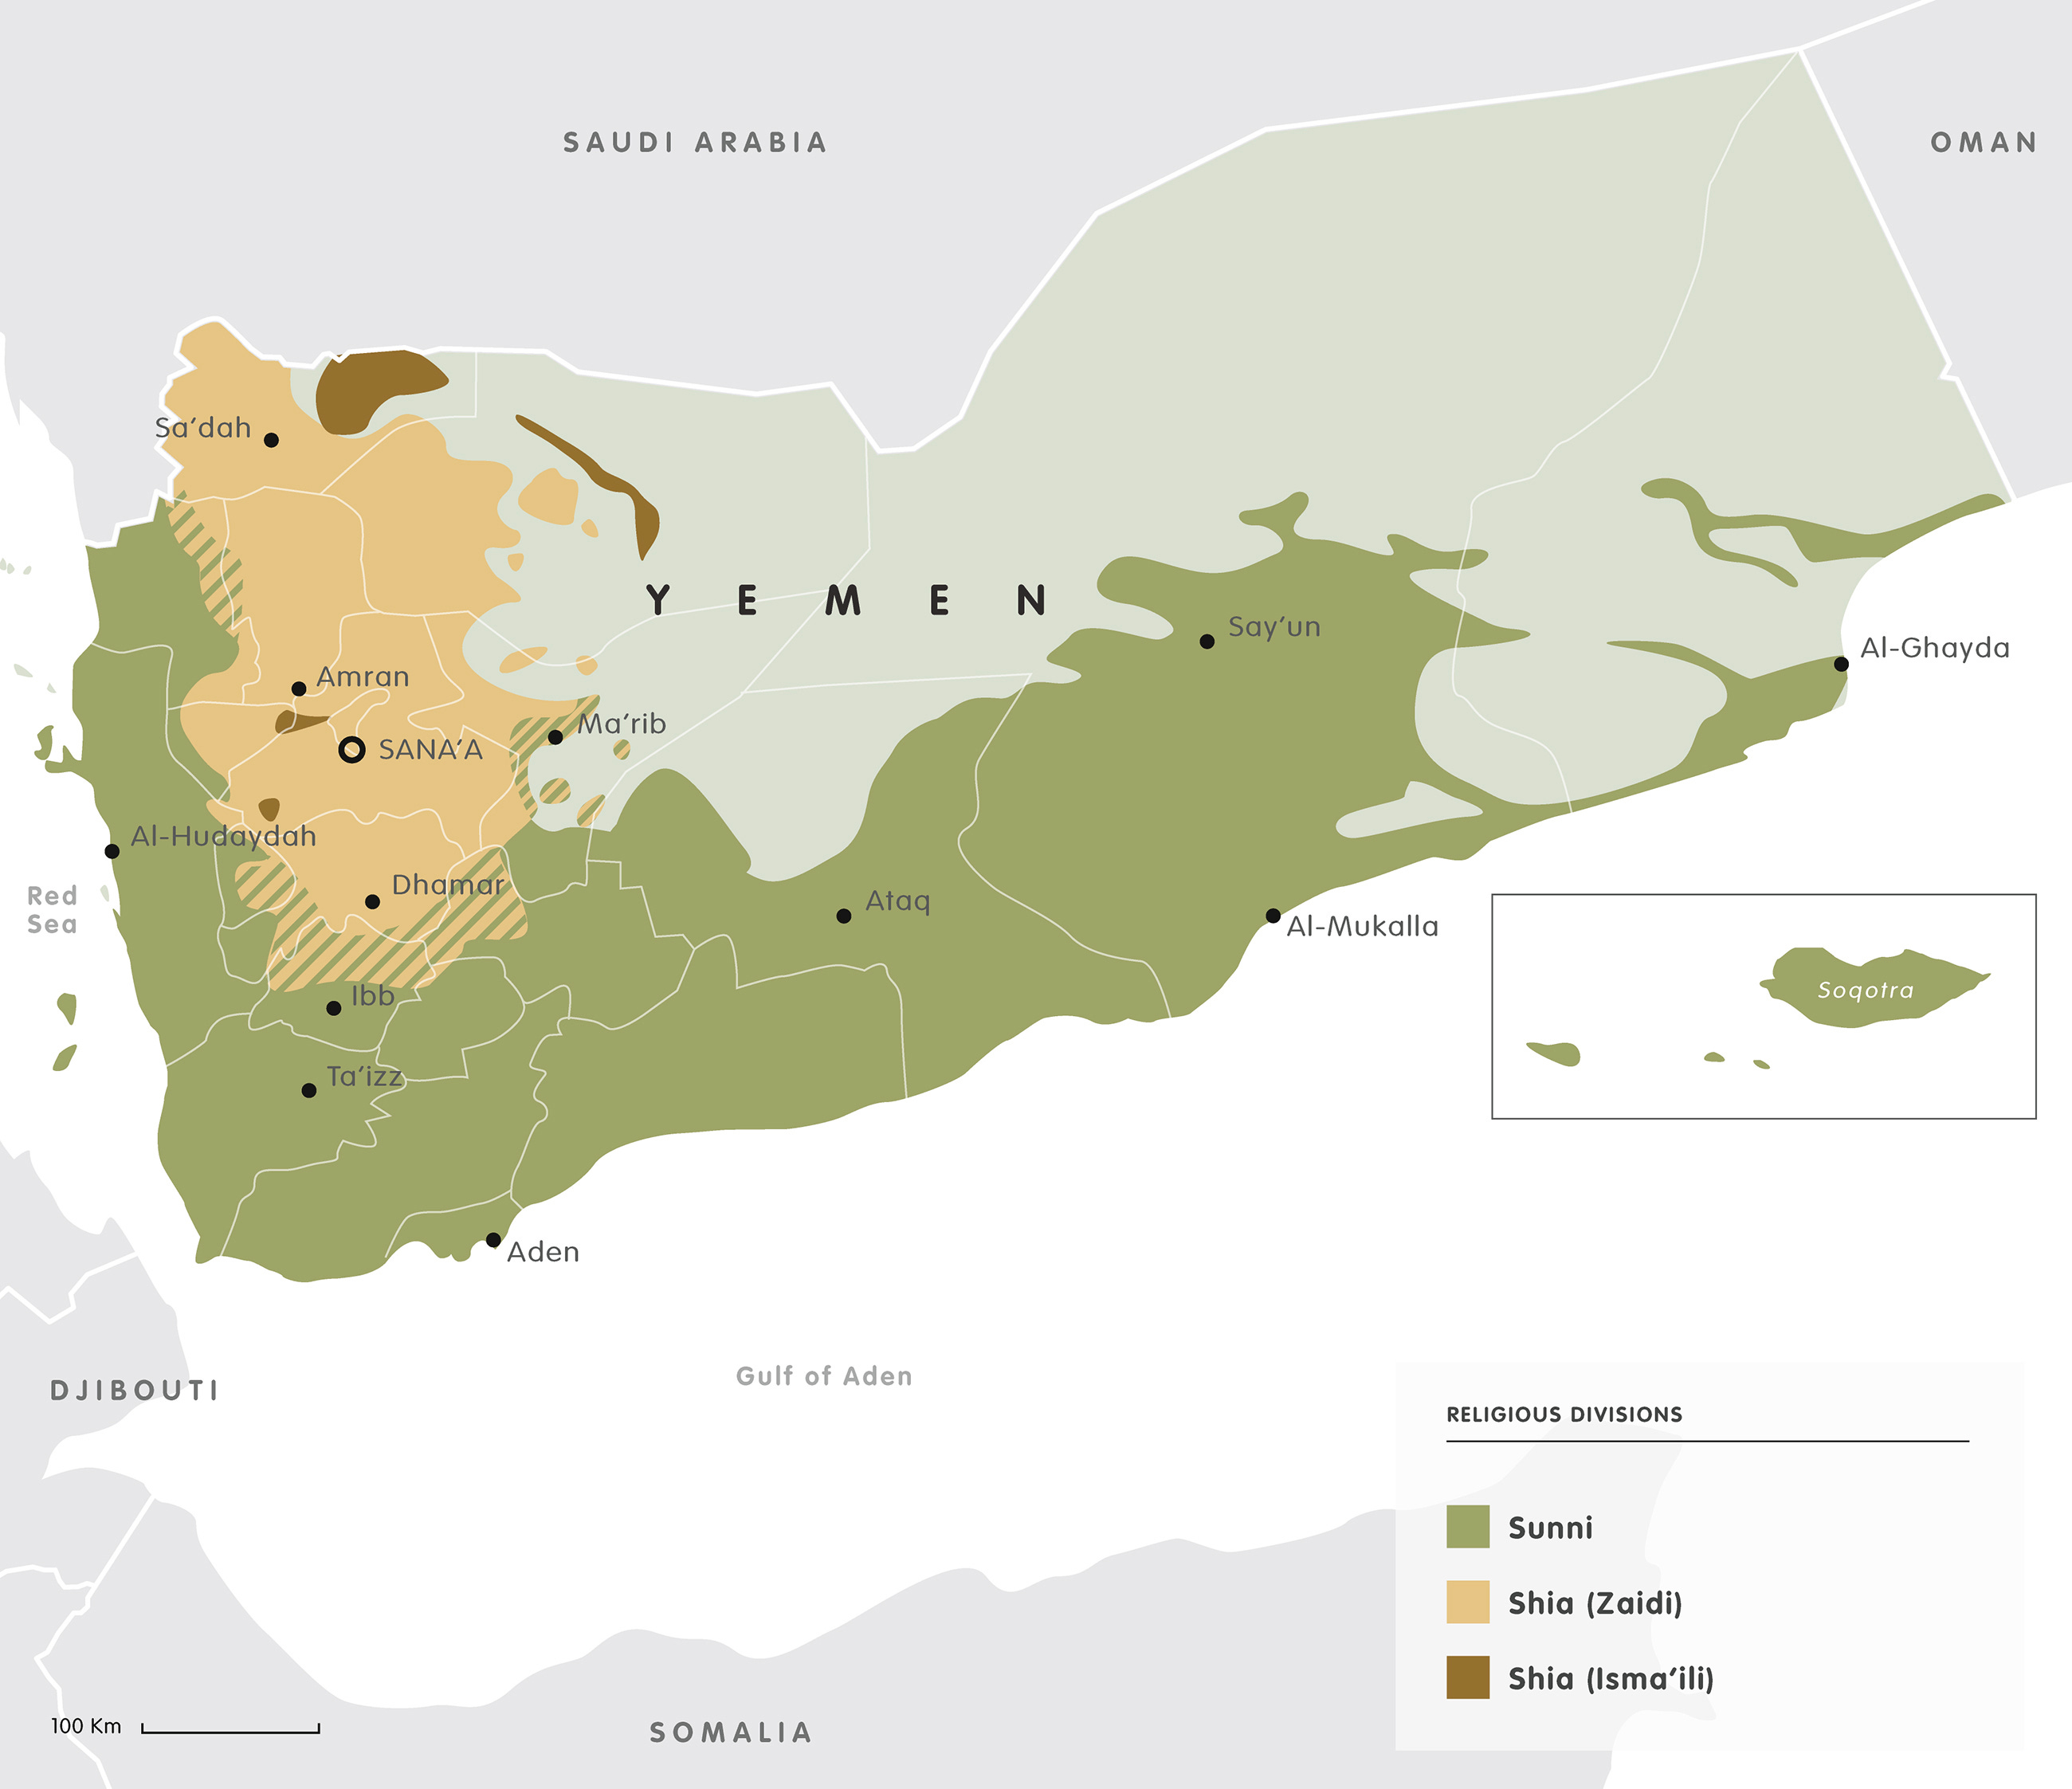
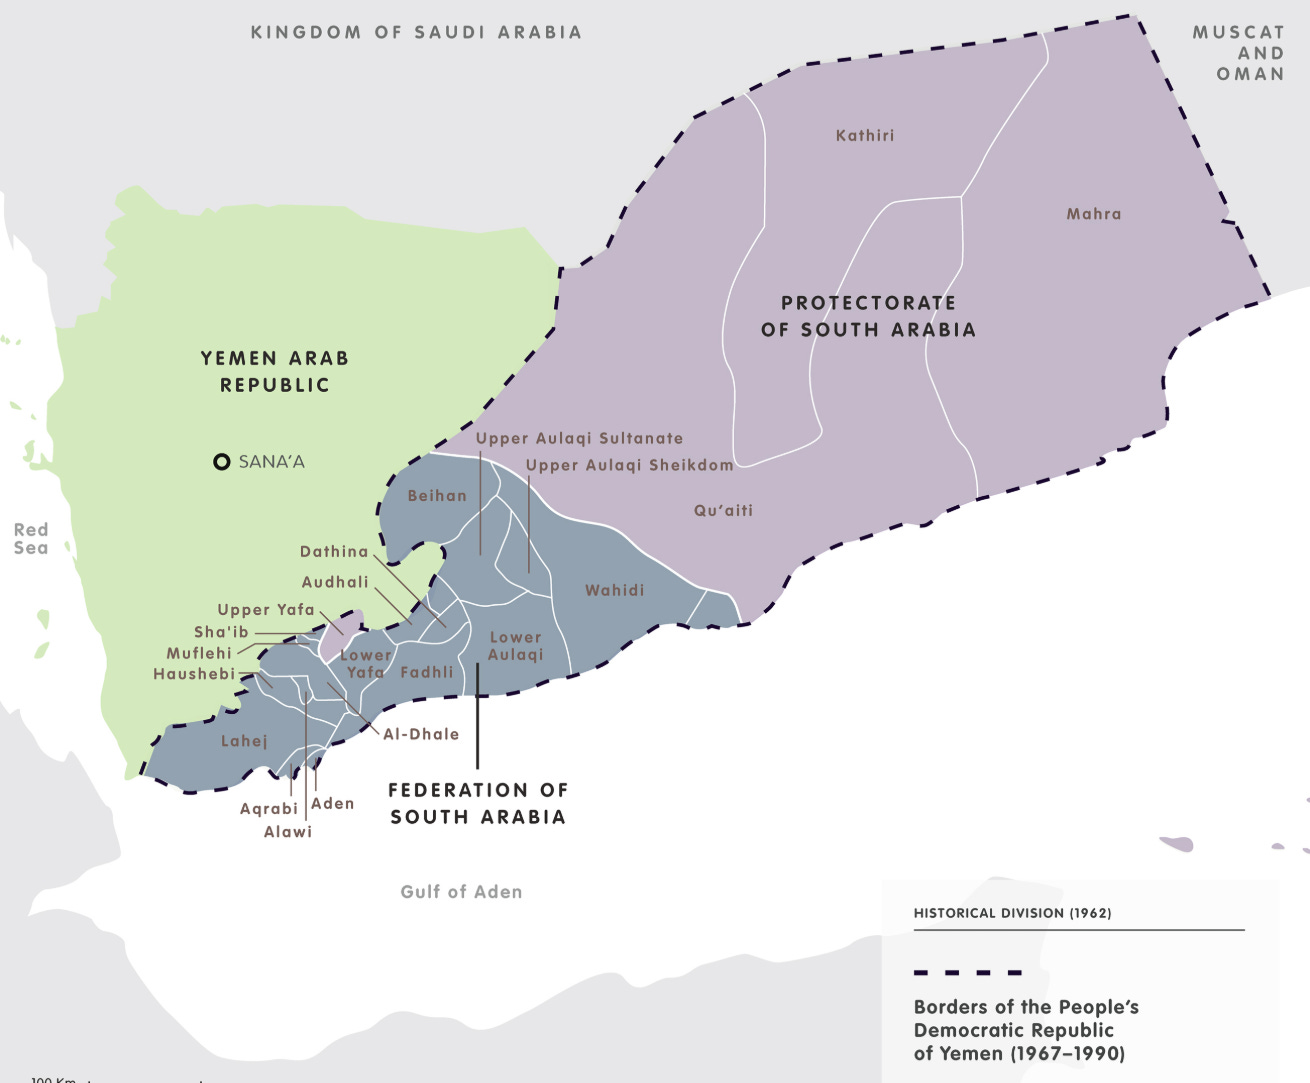
I see that this is really an extension of the war started by The Houthis on Saudi Arabia back in 2019 with the bombing of the Aramco facility. Something discussed last week. The Houthis now have 2 clear objectives. To maintain a control and expand strategy into the Sunni areas depicted in this chart below, and a war offensive within Saudi boarders - Riyadh, Ghawar, Abqaiq, Aramco facilities, The Petroline etc. This is proving to be hugely successful.
Where Saudi forces are ineffective, they are bought in, in the form of mercenaries. These mercenaries are proving to also be ineffective as they have been over run in the past week in the south of Yemen.
Read the Net Net section for the implications
Usurping Europe
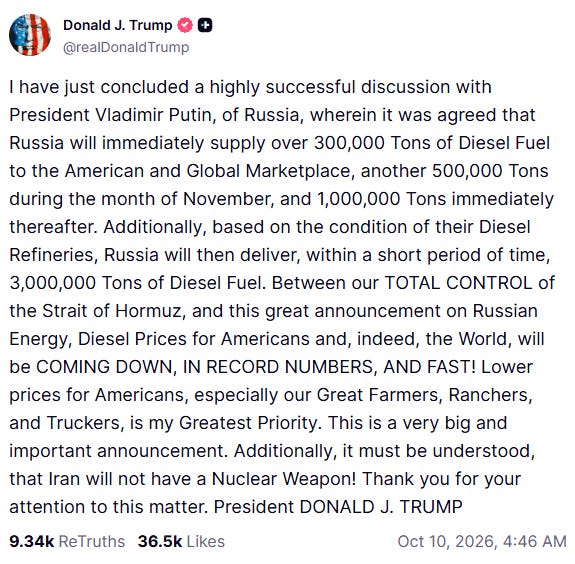
In a surprise announcement late last week, Donald Trump announced that Russia would provide token diesel shipments to The US and in turn the world. The fact that it is only enough to power the worlds diesel demand for a total of 11 minutes is a small element. This is an optics and deal art play. Trump knows if he can bring about even the smallest of deals that it can become a talking point for further negotiations. An effective way to break deadlocks, but also a way to break down the insanity of Europe’s current stance against Russian energy.
The US administration is frustrated with what they see going on in Europe as are most EU citizens. The whole leadership decision structure is broken. NGO scam shops that burn taxpayers money run the roost, while leadership suffers from weakness and wanton stupidity. It is a malicious air that has descended on what was only a few short years ago, a rebounding unified group from The Global financial crisis. Once covid hit, we never recovered. As a European citizen myself, like many others, is disgusted with current policies seen across immigration, social spending and national or pan-European security.
I may not be the biggest Trump fan on the block, but anything happening is better than the current walk into fire. Ireland is currently telling the EU that we want a discount on what we put into the EU budget. France is on the verge of breaking down over budget mis spending on security rather than education and social resources. Spain has had it with their government on Ceuta and housing policies last week, no matter how interesting the new leadership there. Poland’s economy is thriving currently, and they also have had enough with left and far-left leadership in Brussels. The mast of the old world ship is breaking.
It was no surprise to see Boris Johnston come out against Trumps efforts to get Putin and Zelenskyy to agree to an energy ceasefire. Not surprising from a prolific comic of his calibre, that he simply doesn’t understand the current refining crisis rather than oil only crisis.

Do I think that Trump was doing another ‘Reality distortion field’ on Europe, Ukraine and Russia? Yes, like with Steve Jobs to his employees, or Trump’s own negotiations with Iran, he wants to push a narrative and see if it sticks. We saw immediate continued bombings in Ukraine and Russia after this announcement, even with a call from Trump to replace Zelenskyy.
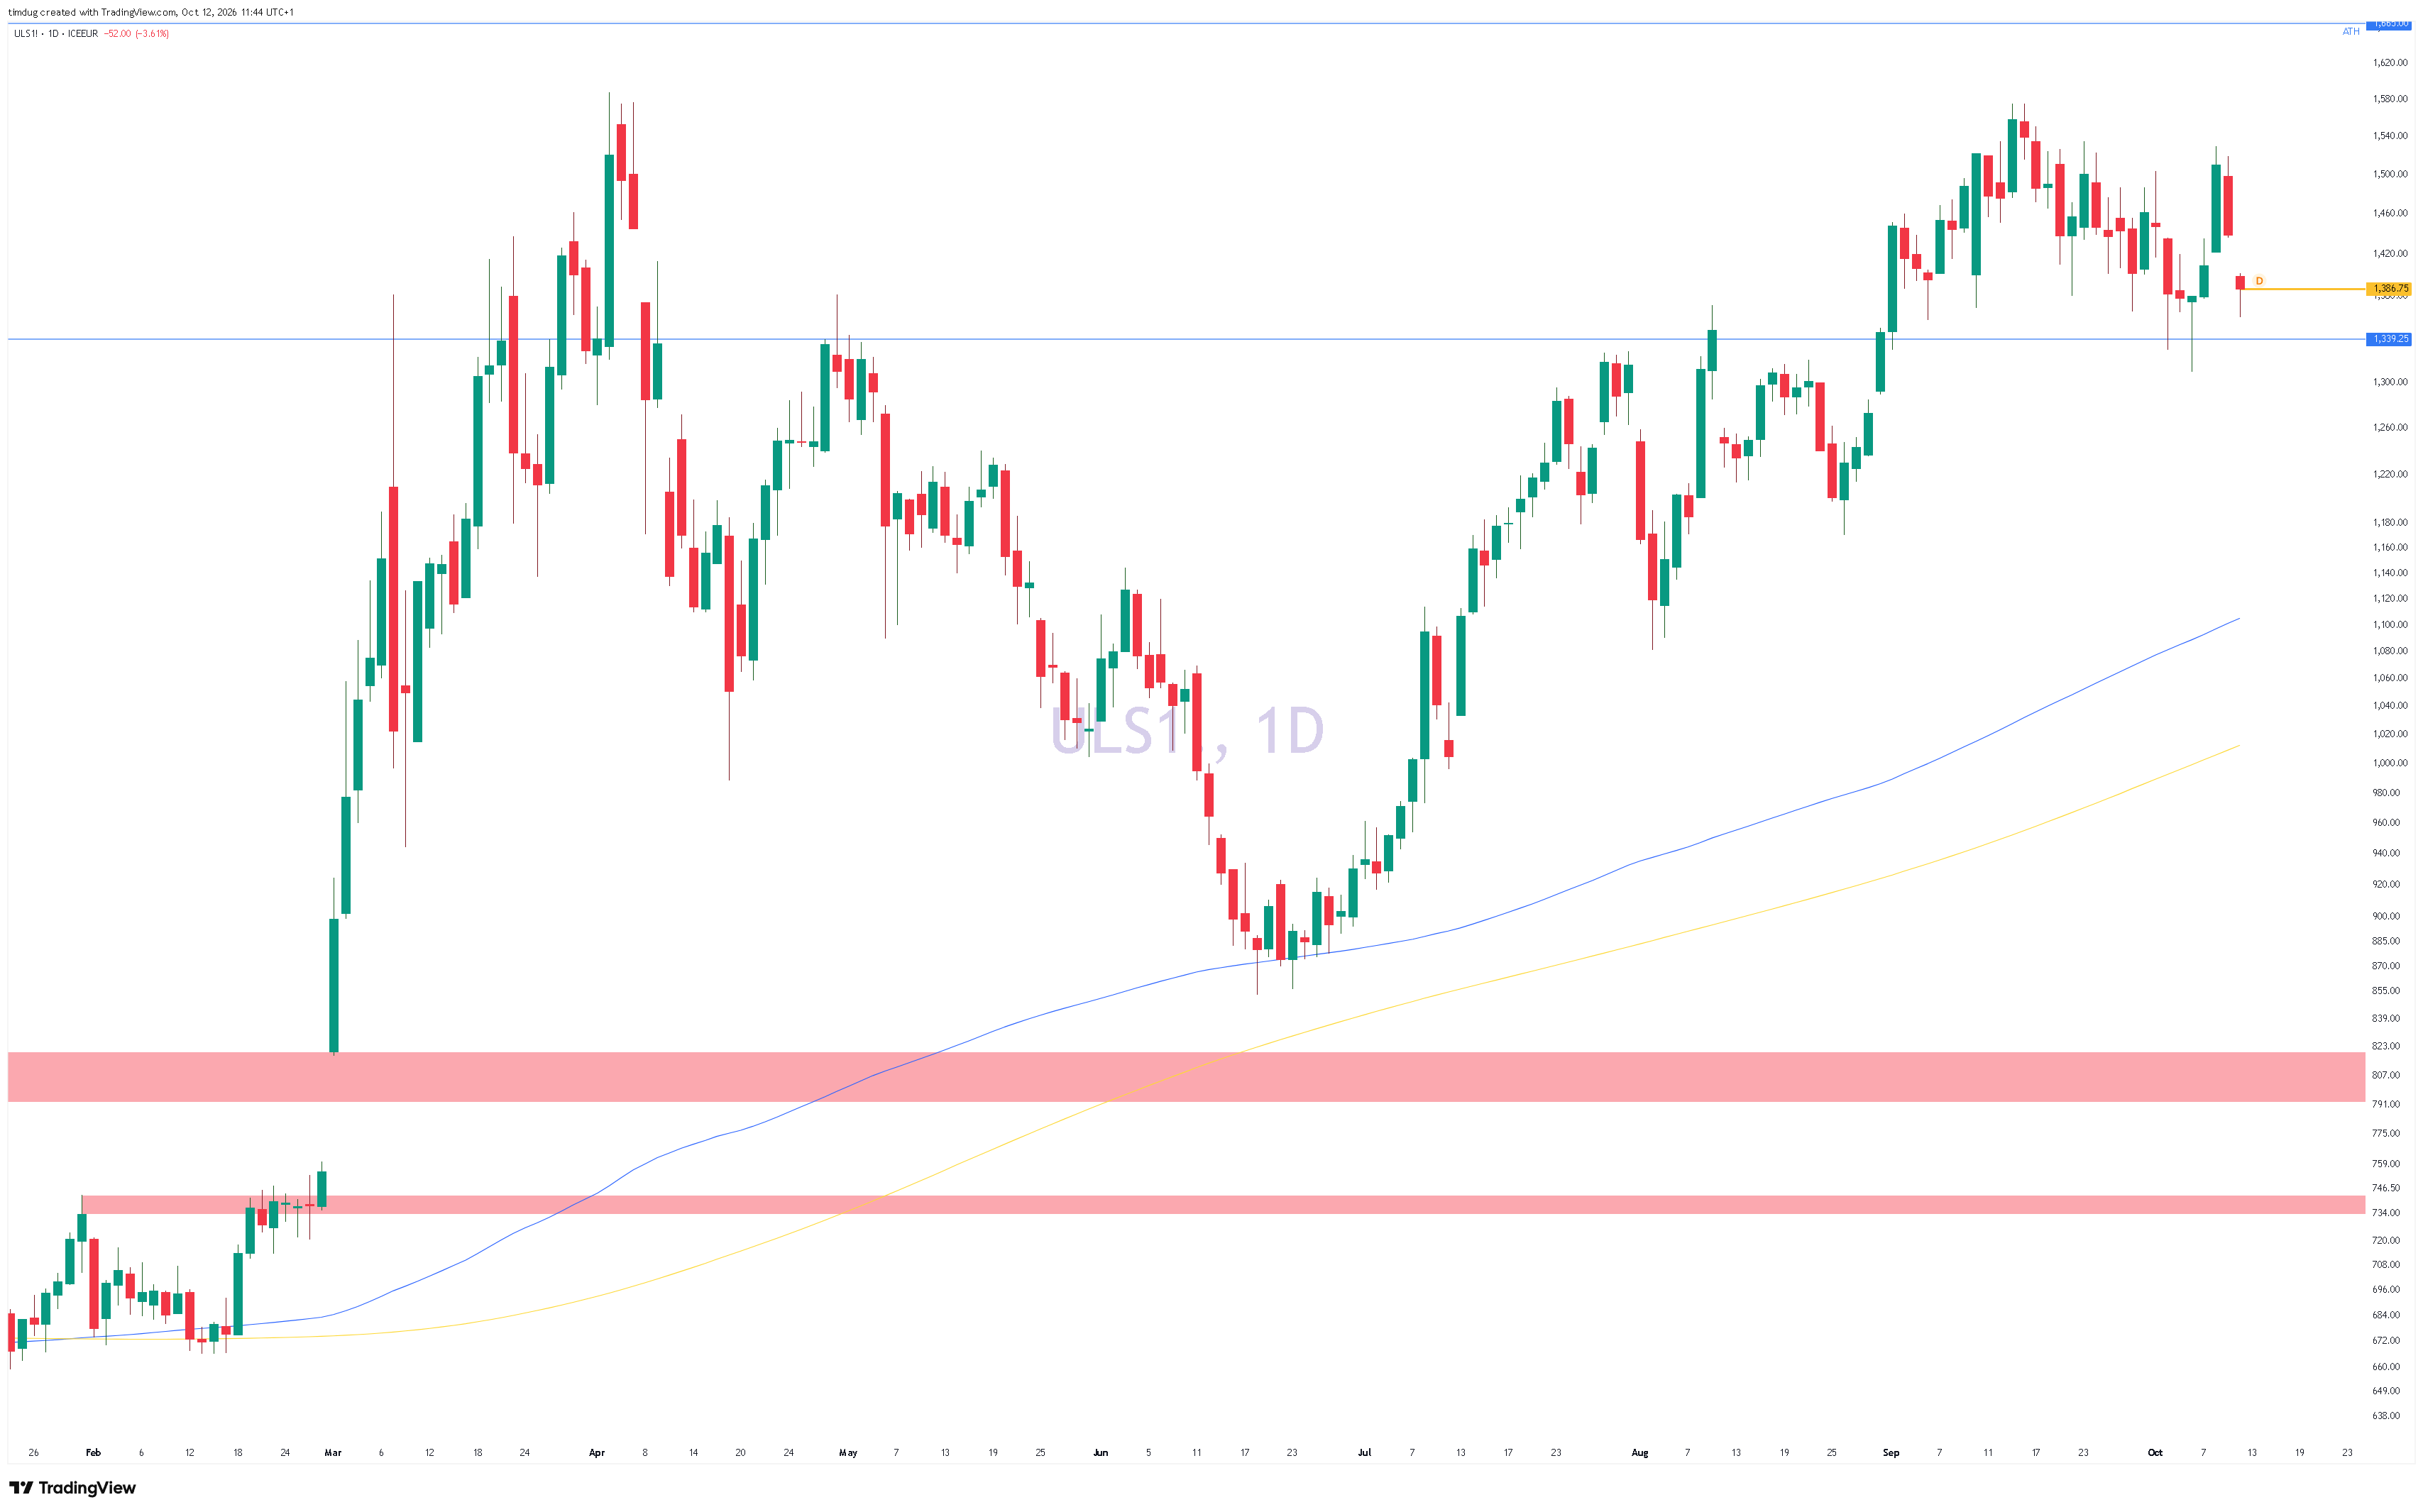
I see this as have a broader soft impact on product prices. Euro diesel-on ICE is down approx 10% from Fridays open at the time of writing, 12.6% off its 2026 high.
The last drop!
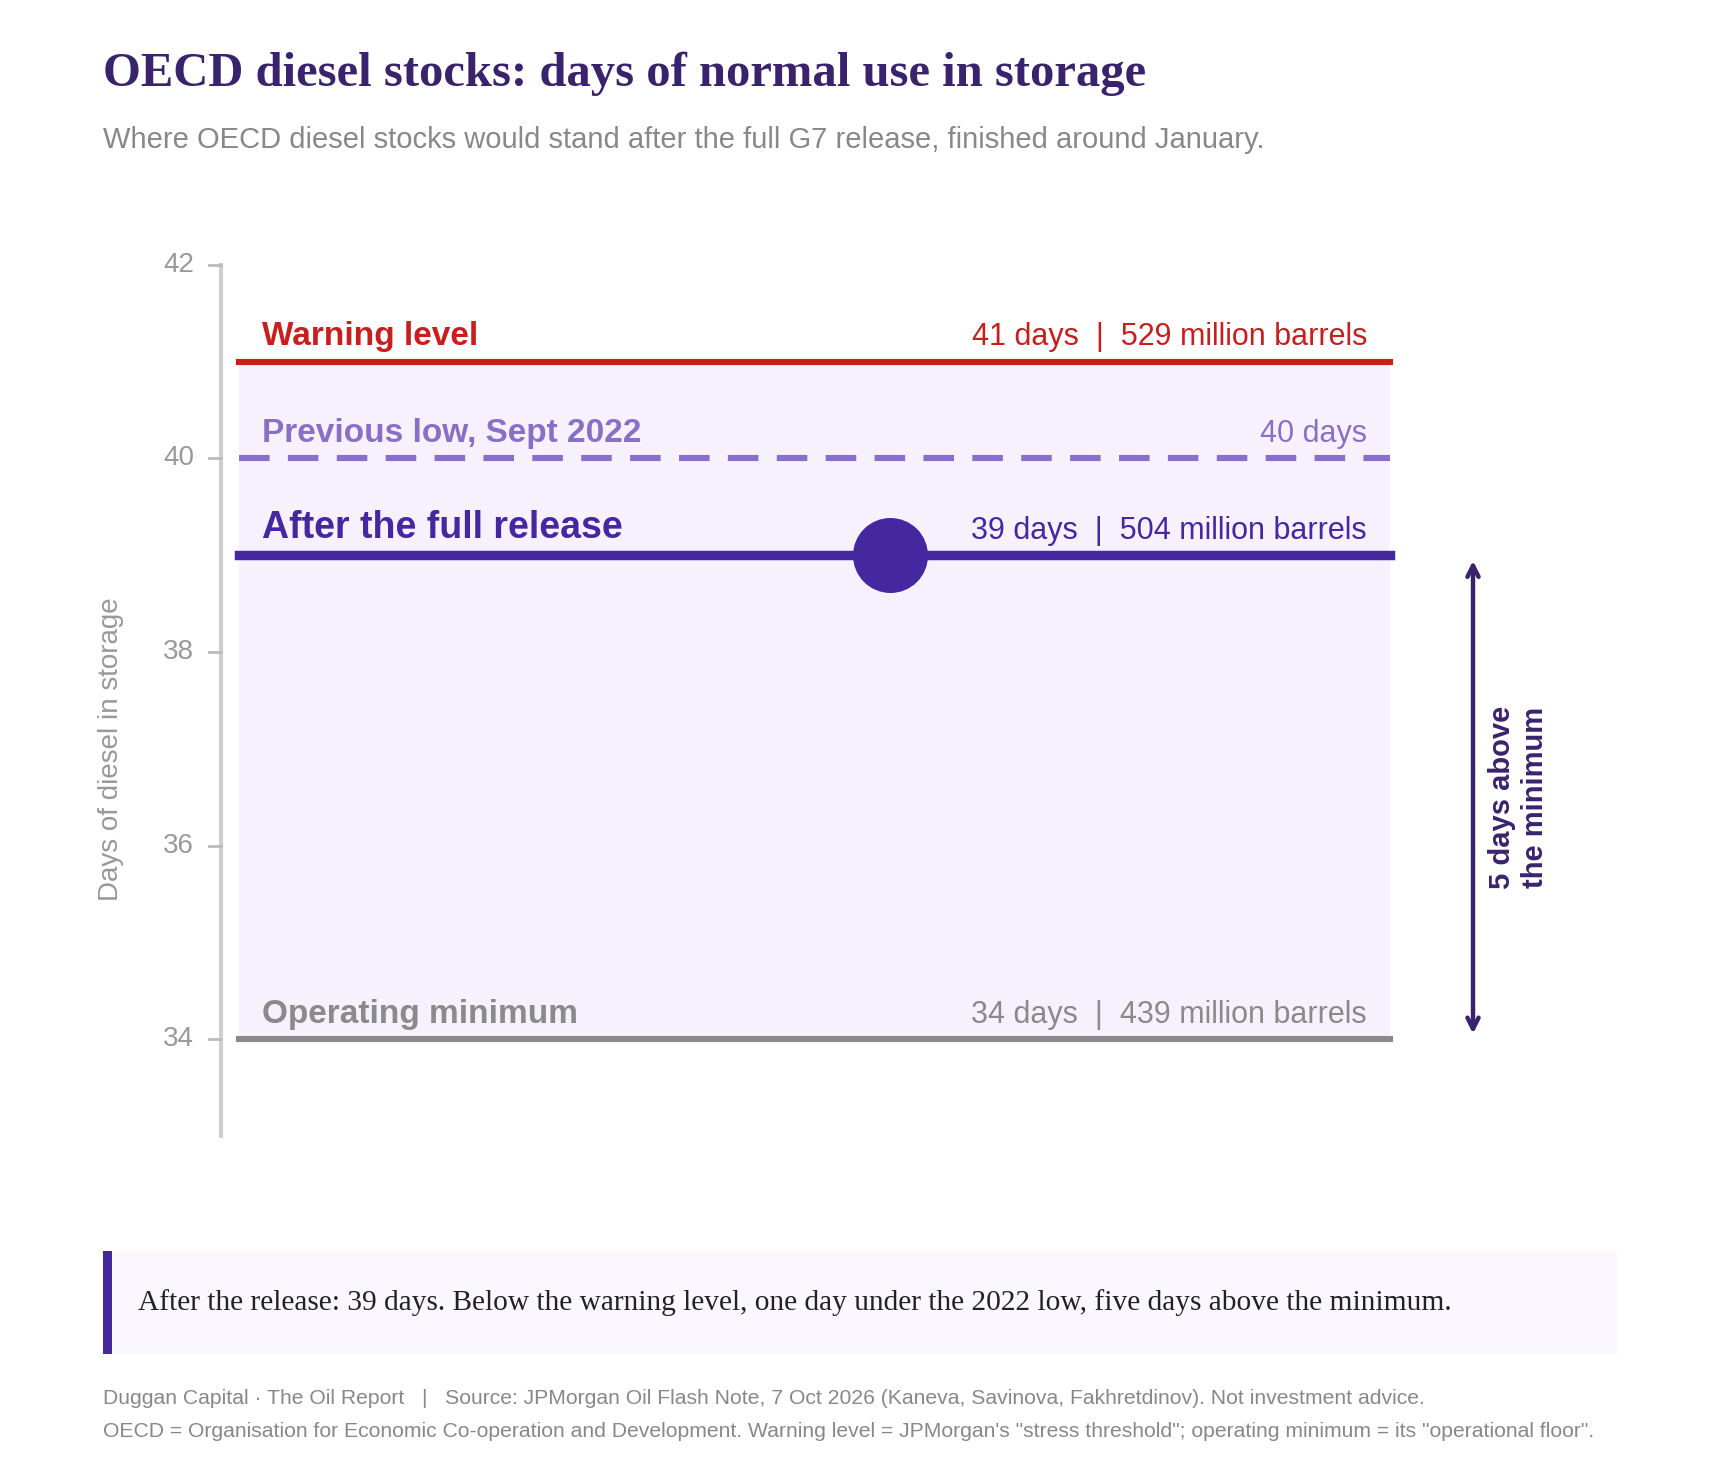
Last week’s announcement from Europe releasing 100mb of crude and products is not actually an additional 100mb. It is simply the remainder of the crude/product stocks agreed in March with the IEA. Out of this remaining 104mb to be precise, they plan to release what is estimated to be 50mb of diesel. Details will be ratified from meetings held this Thursday and Friday. It is important to remember that Europe holds 3x the diesel reserves that the US does. With France and Germany holding chunks of 60mb each. J.P. Morgan released a letter on this all last week, which really went to highlight that Europe has been exceptionally slow to release reserves. Only
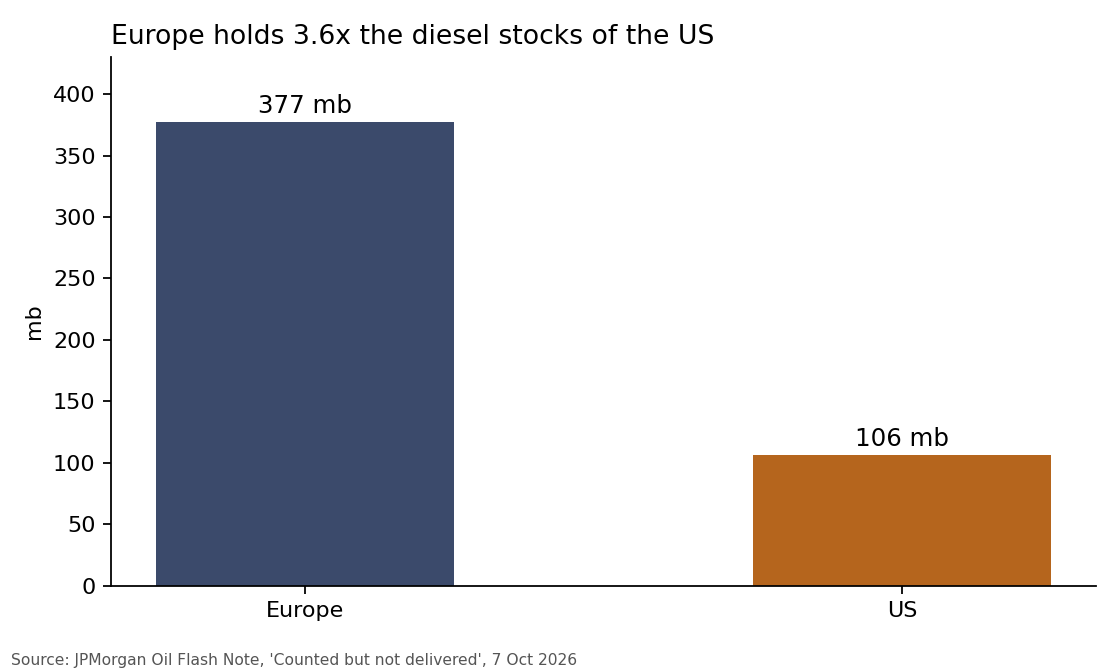
So why is this so significant? If Europe proceed with the next leg of this strategic release, it puts OECD countries below the warning level threshold of 529mb and 41 days of cover, to 504mb of diesel and only 39 days of cover.
Settlement differentials
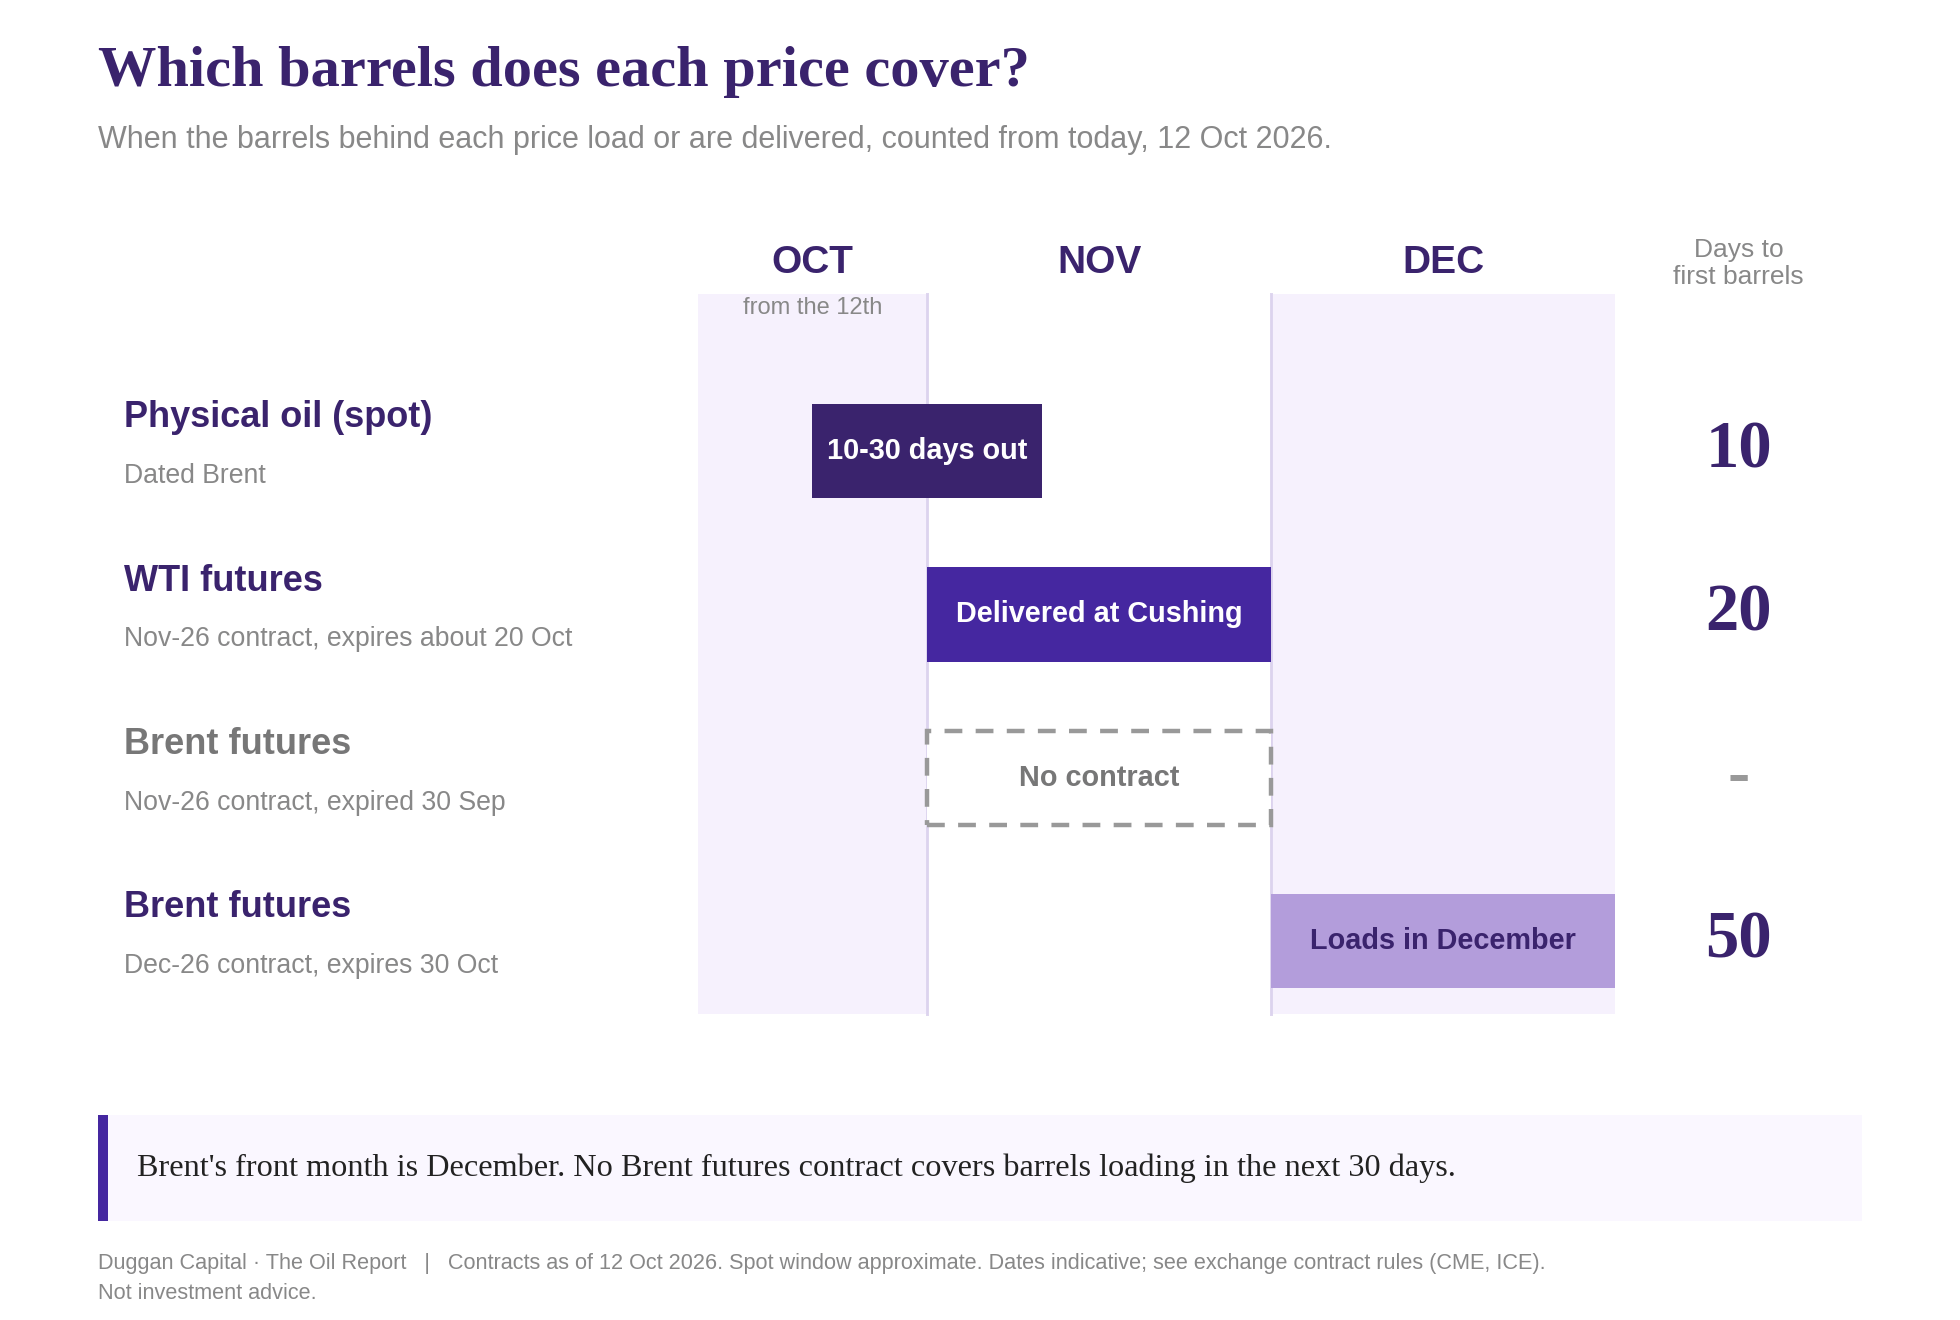
It might not seem like a good time to talk about contract specifications, but trust me, it is. The market for crude benchmarks is working perfectly as designed. Surprising to many, the price for spot settlement is trading well above futures by about $25 at the moment. Futures prices continue to reflect an underpriced barrel of crude that discounts the risk of right now.
With Brent physical spot delivery oil (oil right now) trading $45 above Dec futures $105 (oil delivered in about 30 days). In a large part, the system and markets as they are designed, are trading exactly as they should do. One contract for oil if you want it right now and another contract and price for oil delivered in the future. So you can clearly see there is approx a $45 premium built into oil availability right now, versus $45 discount for brent oil delivered in Dec.
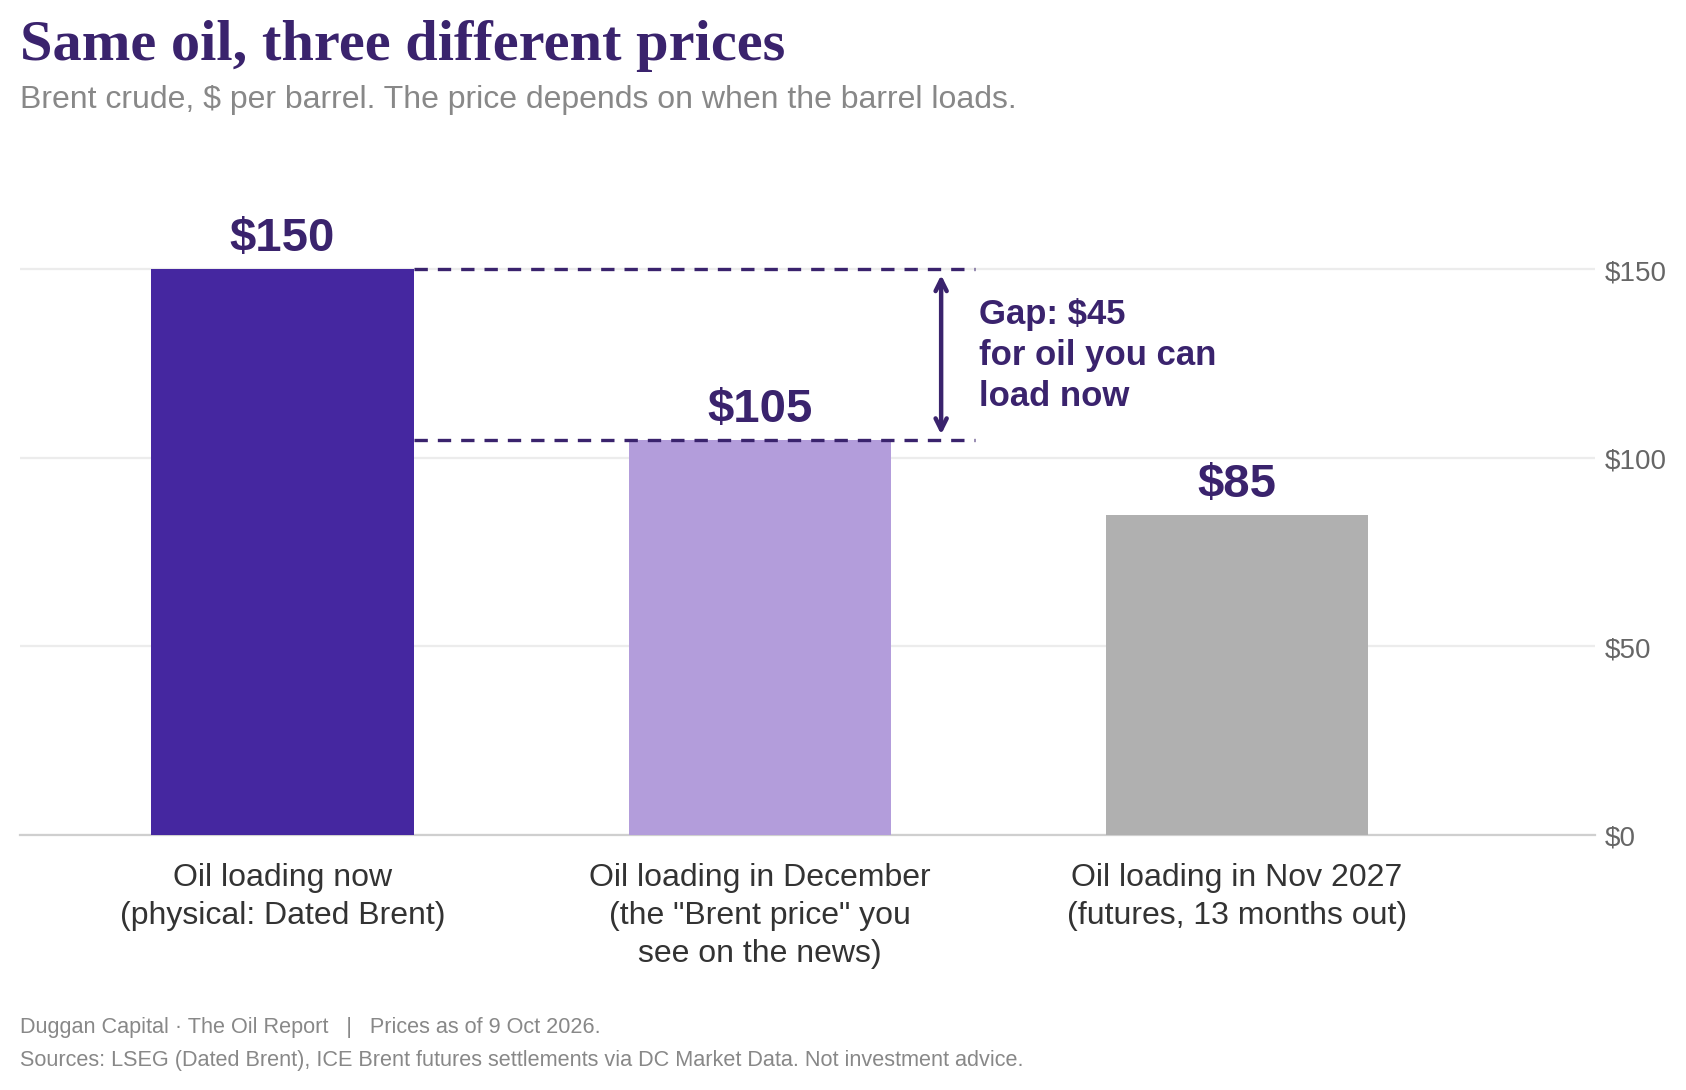
The markets became too comfortable with spot and prompt futures being almost the same price constantly. This was born from prolonged periods of relative stability across international trade and flows - our former globalised world. Now the mechanics of spot and futures come into play, where a deal done today carries a vastly different dynamic and contract settlement spec, than a deal done for delivery of oil in 30 -60 days.
Add to this the actual settlement dynamics of Brent over WTI. With WTI, say you buy a futures contract today (1000 barrels), then those barrels get delivered the first week of the next month. So there is always less than a 30 day wait for delivery and less risk premium in this war.
With Brent, if I buy a futures contract today, it will deliver in the first week of 2 months from now. Therefore, a futures deal on brent carries much more duration risk than WTI. That risk is only amplified in the current situation.