

In this report: Narrative max bearish, US Diesel export ban? Diesel NYMEX & ICE reports added to COT section.
Last week. Brent -5.56% (-$5.75) Open $104.71 H $104.90 L $96.38 C $97.62
Trump said on Tuesday that he supported restricting diesel exports, a move that surprised senior officials and kicked off a search for alternative measures. Speaking in New York on Tuesday, Wright said banning exports was a bad idea and he preferred a voluntary effort, but did not provide specifics-Reuters Sept 24th 2026.
Articles
France to Deploy Forces to Protect Saudi Red Sea Oil Port
Aramco Restores East-West Pipeline as War Risk Closes In on Yanbu
Aramco CEO Eyes “Fourth & Fifth” Oil Export Routes To Break Hormuz Chokehold
Saudi Oil Shipments to Europe Cut After Drone Attacks
Soaring Oil and Gas Prices Push Europe’s Inflation Fight Into 2027
US energy secretary seeks refiners’ help amid narrow options to curb diesel price
If Global Trade Breaks, It’s Worse Than 2008 | Ed Conway
Unwanted in the US, old oil equipment finds a new home in Venezuela -
Americas Offset Some Middle East Oil Supply Issues
Saudi buffer runs thin, Atlantic barrels reprice
Canada’s push to supply Europe with hydrogen is falling short
At Least 2 Killed as Ukraine Strikes Industrial Sites Across Russia
US Data Centre Power Demand Projected to Double by 2027
View
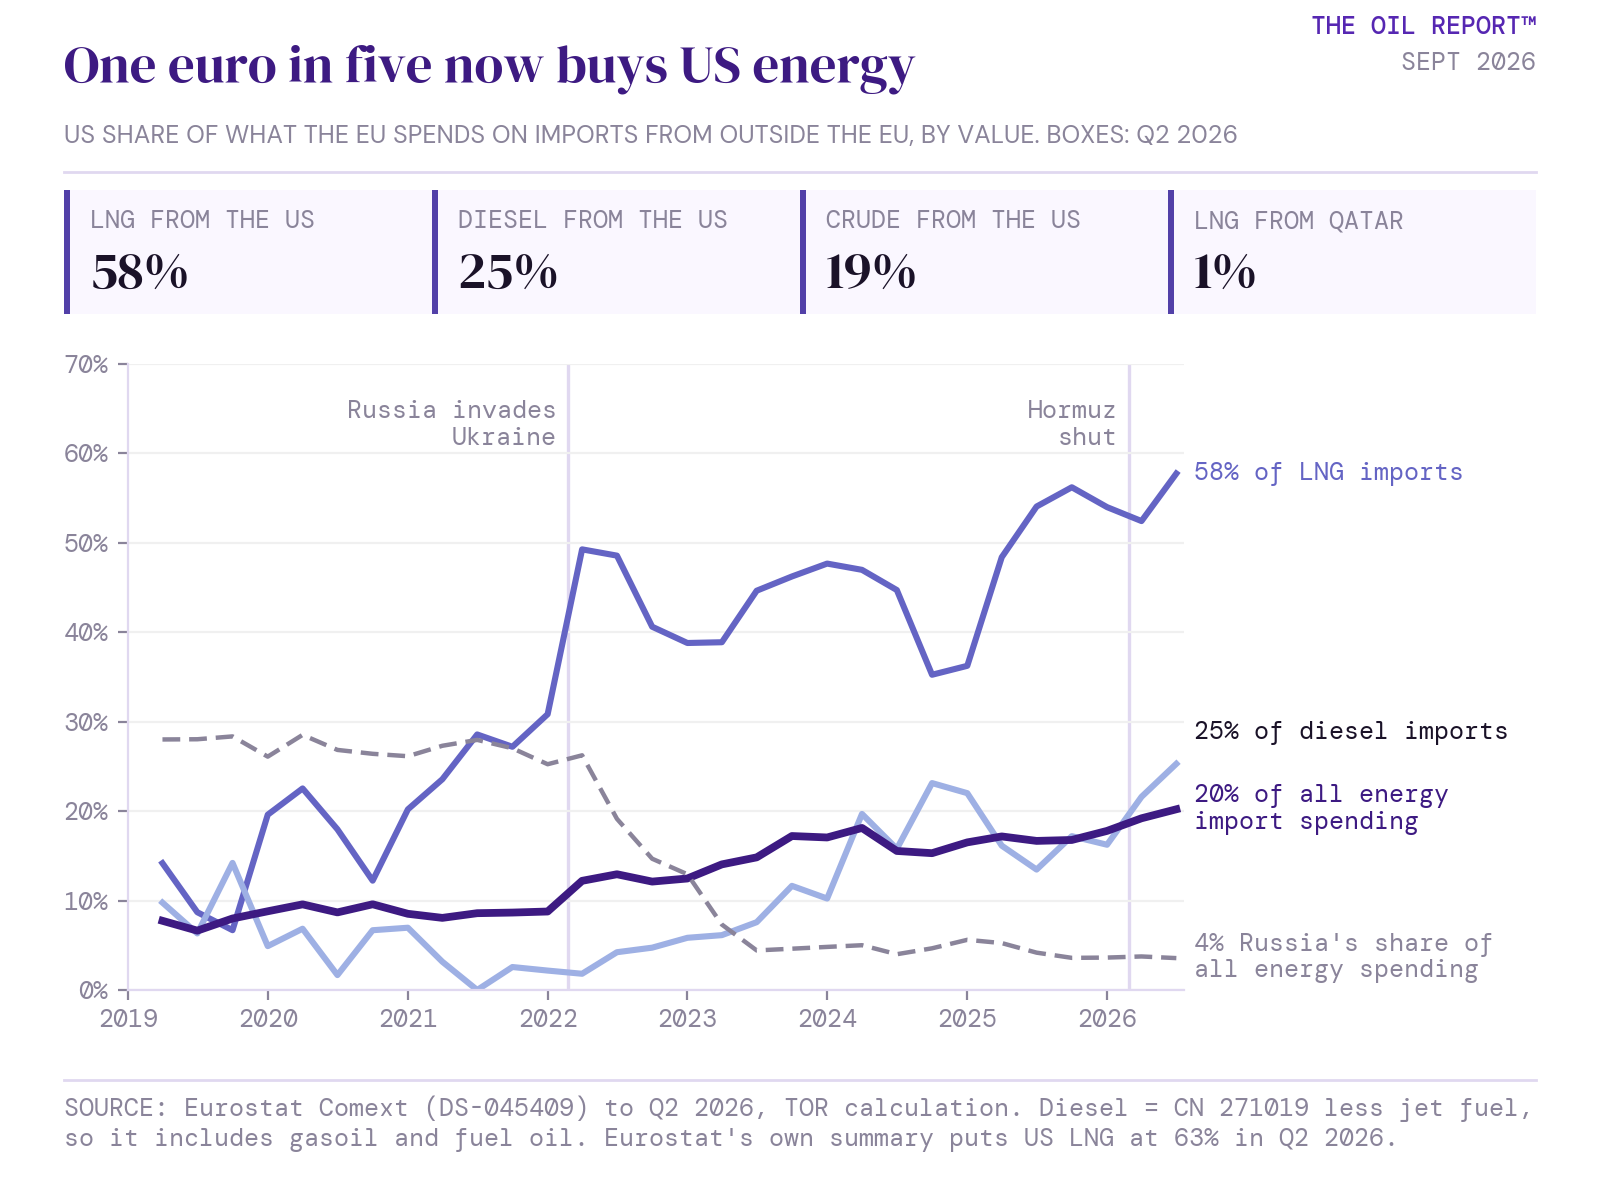
How did we get here? As we face the early winds of what is the largest energy shock in history, Europe is caught in the cross. Having given up Russian LNG and energy imports, we now rely heavily on The US for energy. We have traded a supposed Russian boogeyman for a manacle empire that will assert its dominance today.
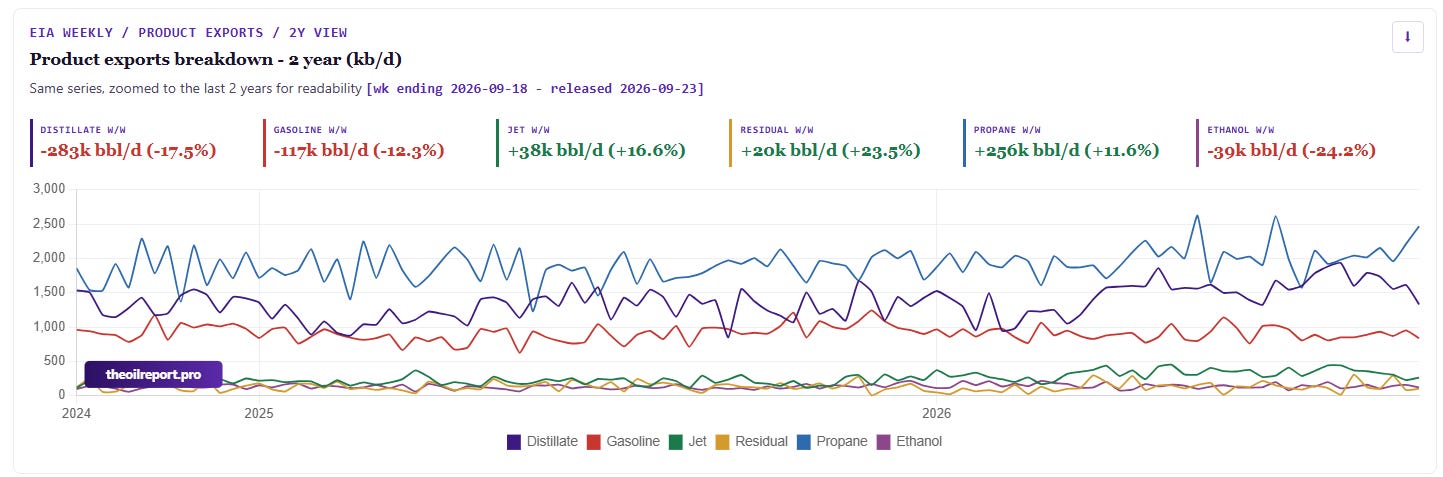
Retailers are fighting for the diesel barrels on a global basis. There is not enough refining utility happening on the planet (with extreme focus on US, China, Middle East) to stem prices from continuing to rip higher. This is the phase of the war where we will get traditional demand destruction regardless of what price crude is. This is where product prices lift so high, that people change habits and stop buying as much, with industrial and agricultural hit the hardest. What comes next from The US administration will make or break modern society. Talk of a US diesel export ban hangs firmly in the energy narrative right now. Below are charts from last weeks EIA reports ‘Products’ section, where we can clearly see US exports of Diesel while inflecting back down, are still relatively high. Will the US simply curtail exports rather than an export ban? All we know is that thanks to 2 war fronts actively encouraged by ‘The West’, the globe has shifted to more reliance than ever in history on US energy exports. The petro dollar is secured! The whole show is simply a market share war. A Euro sandwich in a Trump/Putin bun!
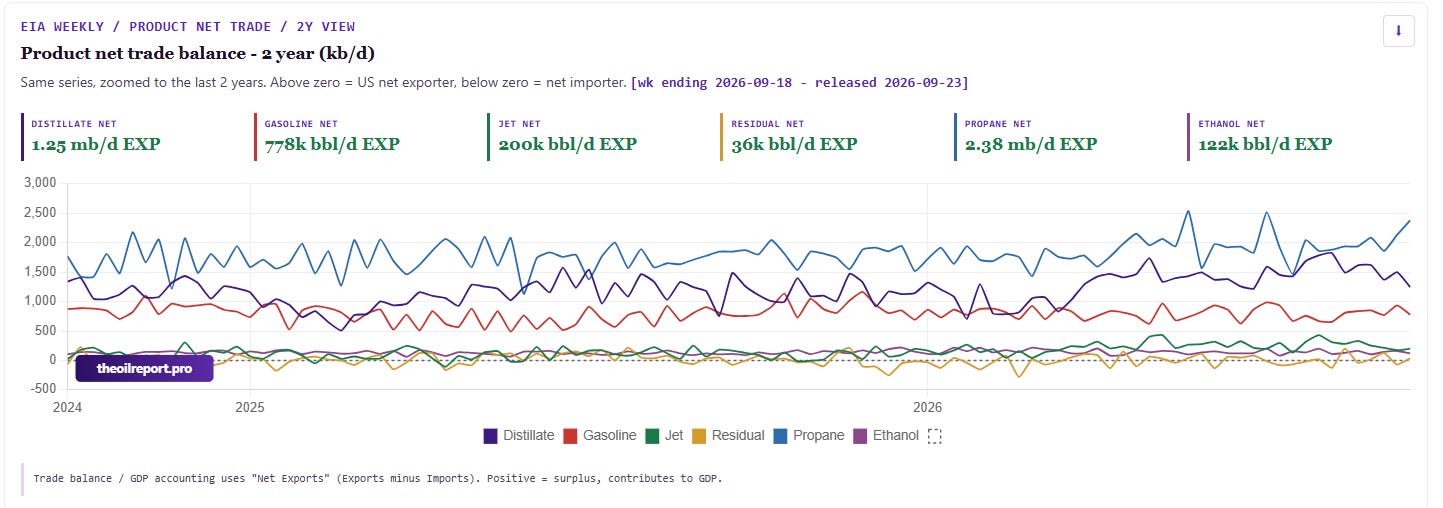
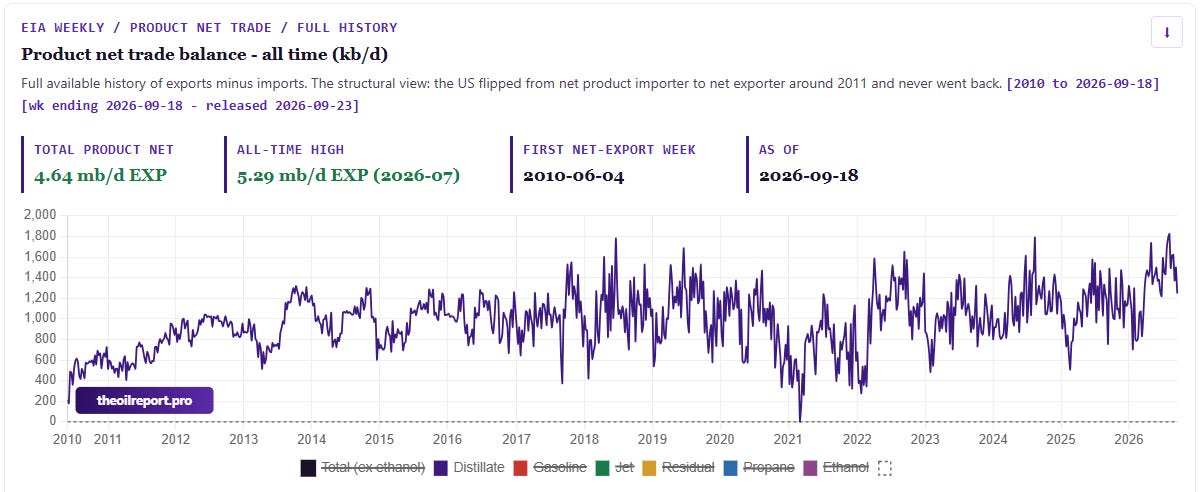
Bearish as f%^k
As late as Saturday, the large energy market intelligence community compiled their ship tracking and barrel counting data. And for the bulls, it couldn’t look any worse. Hormuz Strait Tracker has been doing a wonderful job at tracking ships and loadings 24/7 for many months now. Utilising 2 satellite feeds and using smart methods that some very expensive market intelligence firms have not. They have the average daily flows of oil now at 16.6mbpd, 83% of pre war flows. Specifically crude flows have recovered to 89% pre war.
Commodity context marked it as at 13.5mbpd and probably on the shy side. Kpler are quoted in Reuters as of 2 days ago at much lower figures of 33million for the week, so about 4.7mbpd and 49.2mb for the prior week, (7mbpd). Tanker trackers have it at 10.5mbpd. I tend to follow their number. So the spread continues to be a complete joke. But net- net, we see a market that overall is completely shrugging off Iranian and Houthi risk. Nothing unusual there!
So in summary.
Hormuzstraittracker.com 16.6mbpd
Commodity Context 13.5mbpd
Kpler 4.7mbpd
Tankertrackers.com 10.5mbpd
Spread 11.9mbpd
Mean 11.3mbpd
This is an insane spread, with a low of 23% of pre war to 83% of pre war levels. It is quickly easy to take the whole lot and turf them out the window. HOWEVER, the reason I want to cover this, is that in such situations, as is the nature of the market, it will trade the consensus and the greater narrative that is laid down. NOT the facts!
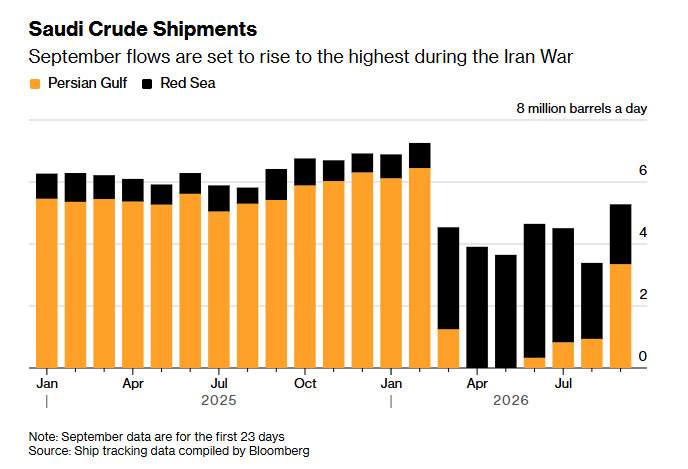
Counter to this bearish narrative, we cannot disregard the bullish elements still within the market. We have not completely cleared the risk factor of ‘what will Iran and The Houthis think of next’? Read The Net Net section below and The COT as there is a 20% change in MM flows.
Something is going on with China that has to be noted. The awesome Lakshmi Sreekumar has been tracking that their purchasing program has gone flat recently. A much loved element for the bulls in recent trade. Is this a sign of another step off global purchases?


Canada NOT YET… to the rescue!
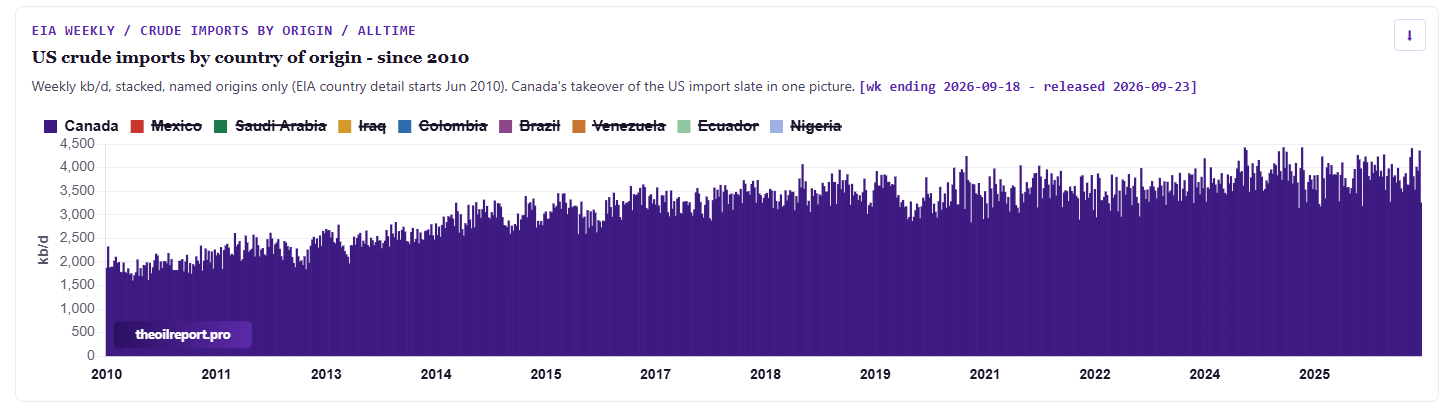
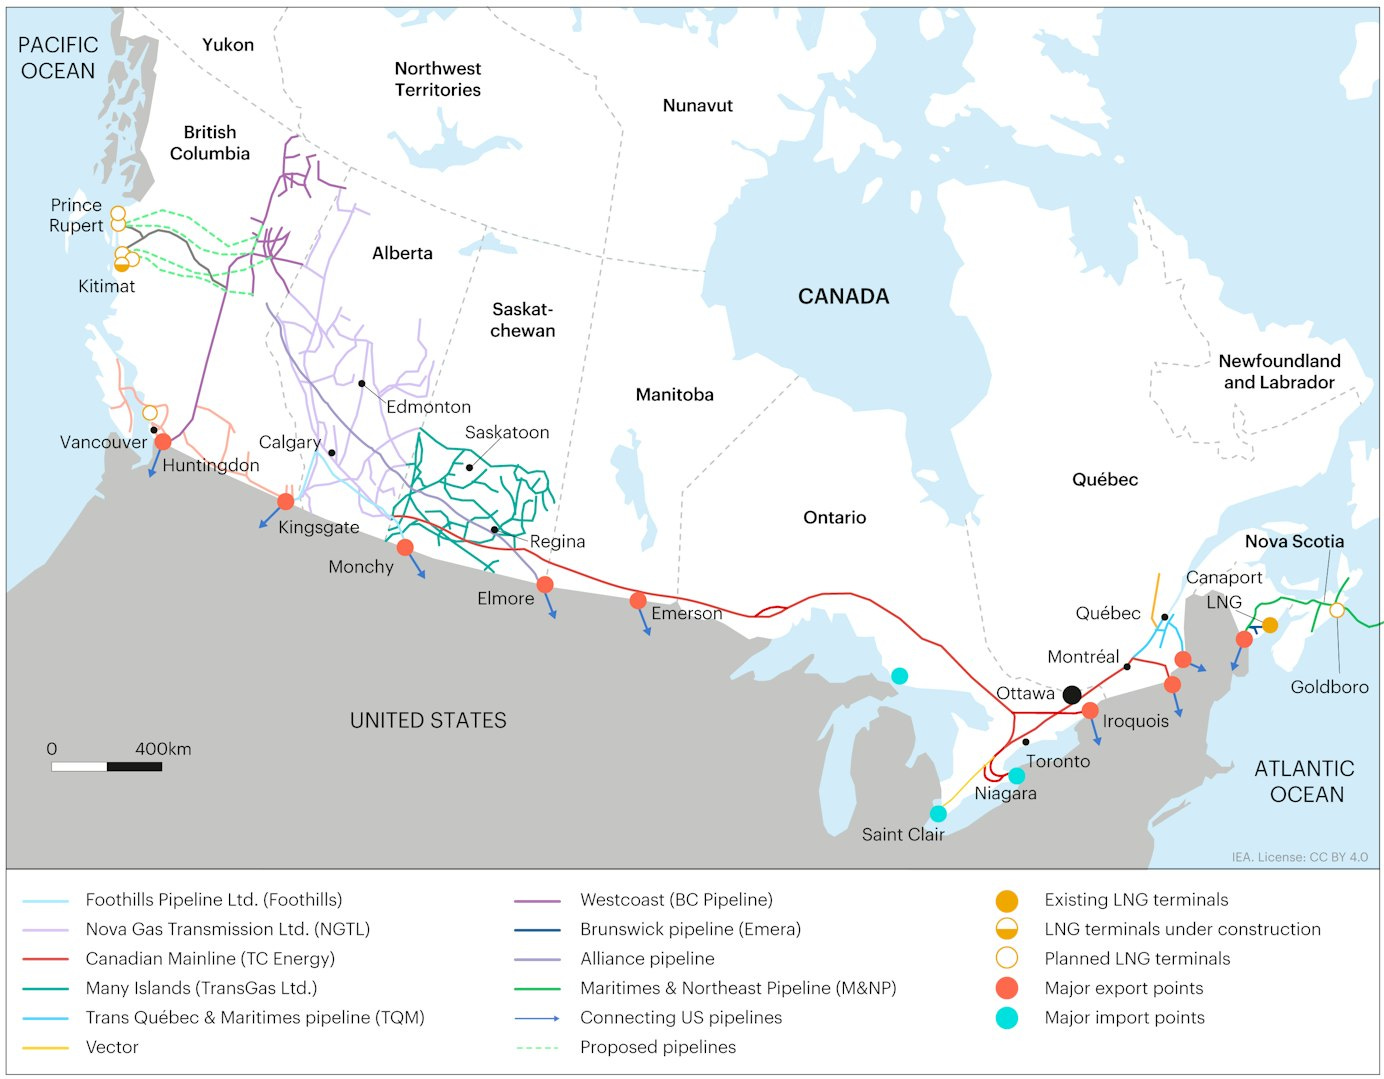
Canada exported 5 million barrels a day last year and sent 4.3 million, nine in every ten of them to the US (Canada Energy Regulator). Its three main export pipelines ran 85% to 95% full. The only one that reaches the sea, Trans Mountain, ends in Vancouver and sends most of its oil to Asia. So Canada cannot ship its oil to Europe in this crisis. It helps another way. Canadian heavy crude keeps American refineries running, which frees up American oil for export, and the US was Europe’s biggest crude supplier last year (Eurostat). That help runs through Washington. There, the Energy Secretary is sounding out refiners on limiting diesel exports, and the President has called the associate-member idea a possible “hostile act”. So despite Carneys love-in Euro affair, America still holds the hose.
Gas is where the deal has substance, but it arrives late. Two German buyers, Uniper and SEFE, have lined up Canadian liquefied gas from a terminal planned on British Columbia’s Pacific coast, with first deliveries in 2032 (Natural Resources Canada). That volume is about 3% of the liquefied gas Europe imported last year. It lands five years after Europe’s ban on Russian liquefied gas, fully in force from 1 January, removes a volume more than four times larger. Canada’s Atlantic coast is eight days’ sailing from Rotterdam, six days closer than the US Gulf, yet not one export terminal or pipeline there has been approved. We have seen this before. The 2022 Canada-Germany hydrogen pact promised exports “starting in 2025”, and its flagship project was shelved this January. So has the love-in jumped the shark? The speeches have. The commitment is real, but every handshake is dated 2025 or 2026 and every delivery 2029 or later. The Montreal summit in late October is the test. If it names an Atlantic export project with a European buyer and a start date, the alliance is real. If not, this is a 2032 story and little respite for European energy prices.
Venezuela
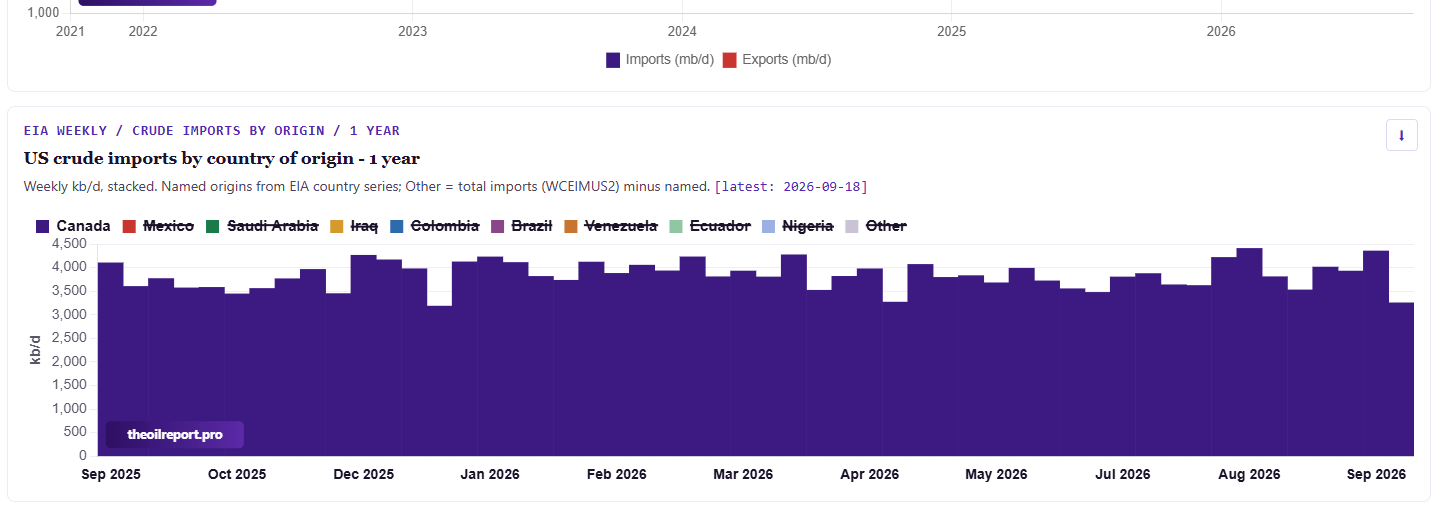
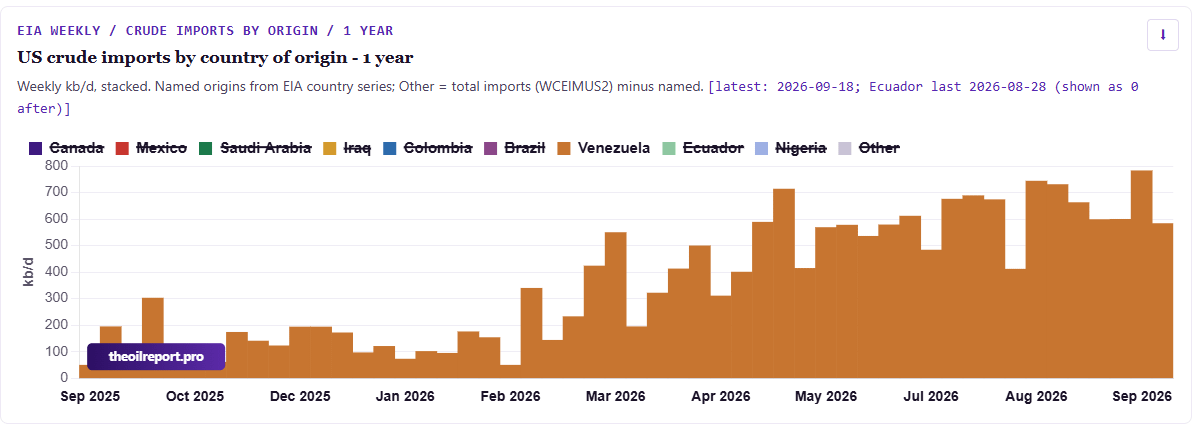
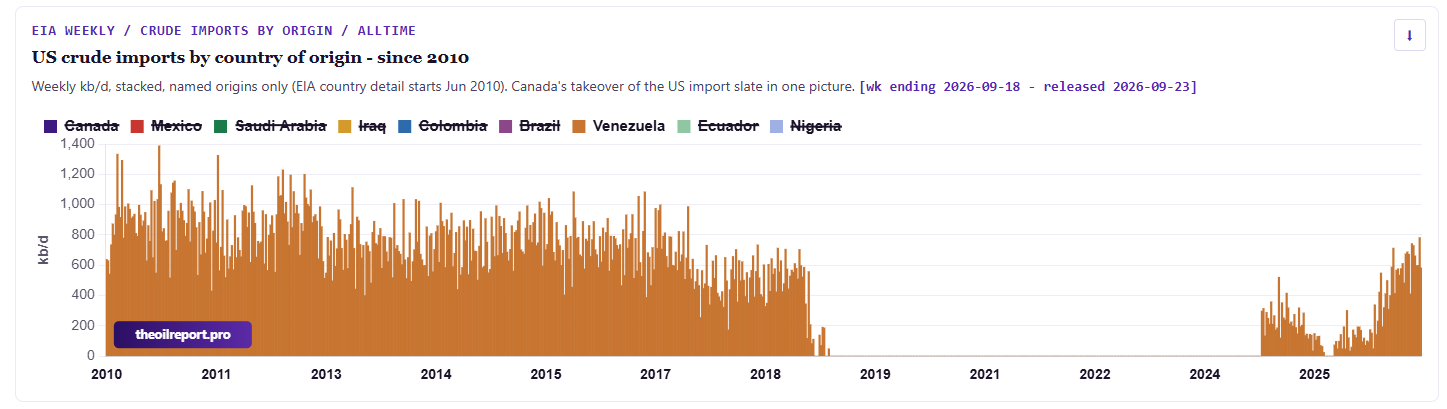
Not much to say here, but important to note that YES, VZ exports to US have risen as we all know, but at the same time, Canada is dropping off in the last 2 weeks. Lets just keep an eye on this.
The Net Net
Below you get my rounded summary, the trade charts and spread trades I’m looking at and the COT for ICE Brent and NYMEX WTI and this week, I also have the diesel COT from both NYMEX and ICE.
