

In this report: Talks in Tehran, ships in the Strait, Kpler's demand cut, thin US diesel stocks, Big seasonal spread and front month moves ahoy and The Commitment of Traders report.
Last week. Brent -2.82% (-$3.29) O $115.88 H $117.44 L $109.02 C $113.43
Note: I’ll be switching to publishing on Mondays going forward. Publishing on Sundays has forced me to finalise views and the macro view by Sunday mornings, thus leaving out how the market reopens, important new headlines and changes in narrative. Last Sunday/Monday was a case where that led to an out of date view.
If I see that there are significant items that must be covered pre reopen on electronic, I’ll push these out in a thread for paid subs over the weekend.
The COT for WTI NYMEX, BRENT on ICE and the combined report (as you get below in each article), continue to be available in our Discord COT channel, immediately after they are released on Fridays.
Thank you for following of The Oil Report is truly appreciated, and the feedback everywhere is wonderful. The chat in our Discord and the small community we have built is also really great. May it grow further into 2027. I’ll soon be moving the email communication to our domain theoilreport.pro and emails you get will change to coming from either tim@ or info@theoilreport.pro. I’ll write a note to all when we plan to do that, but everything else stays the same regarding substack.
Articles
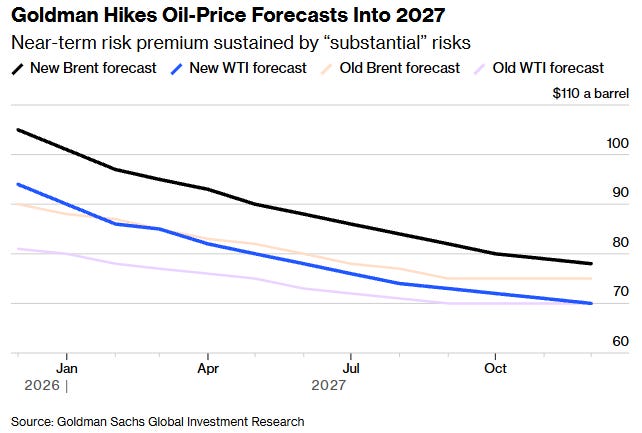
Goldman Hikes Oil Forecasts on ‘Substantial’ Risks to Supply
Oil drops over 4% on hopes of progress in talks on ending US-Iran war
From the Mecca defence pact to Tehran talks: Is the Middle East's security landscape shifting?
Saudi defence pact countries push for peace in Tehran as Houthis launch more attacks
Refined products demand to fall 2.4 mbd in 2026 before an uneven 2027 recovery
OPEC+ keeps December oil output targets steady ahead of tougher call for 2027
The FT: BP’s profits surge to record on high fuel prices
View
Higher for longer and the glut. In short, 8 months of a war means higher baselines for crude benchmarks. There are whiffs of a 2027 glut talk percolating through market narratives at this point, which will start to price in around mid-January which is the Brent contract we trade now. This is the only hope we have of escaping a floor price of $80 brent, rather than a ceiling. The only problem with glut talk is that each time it is mentioned, a nice clear model of how and when this war ends is presented. If you have been reading along here since March, you will know that gets shifted around almost hourly. Between White House/Trump jawboning and Iranian/Hormuz realities.
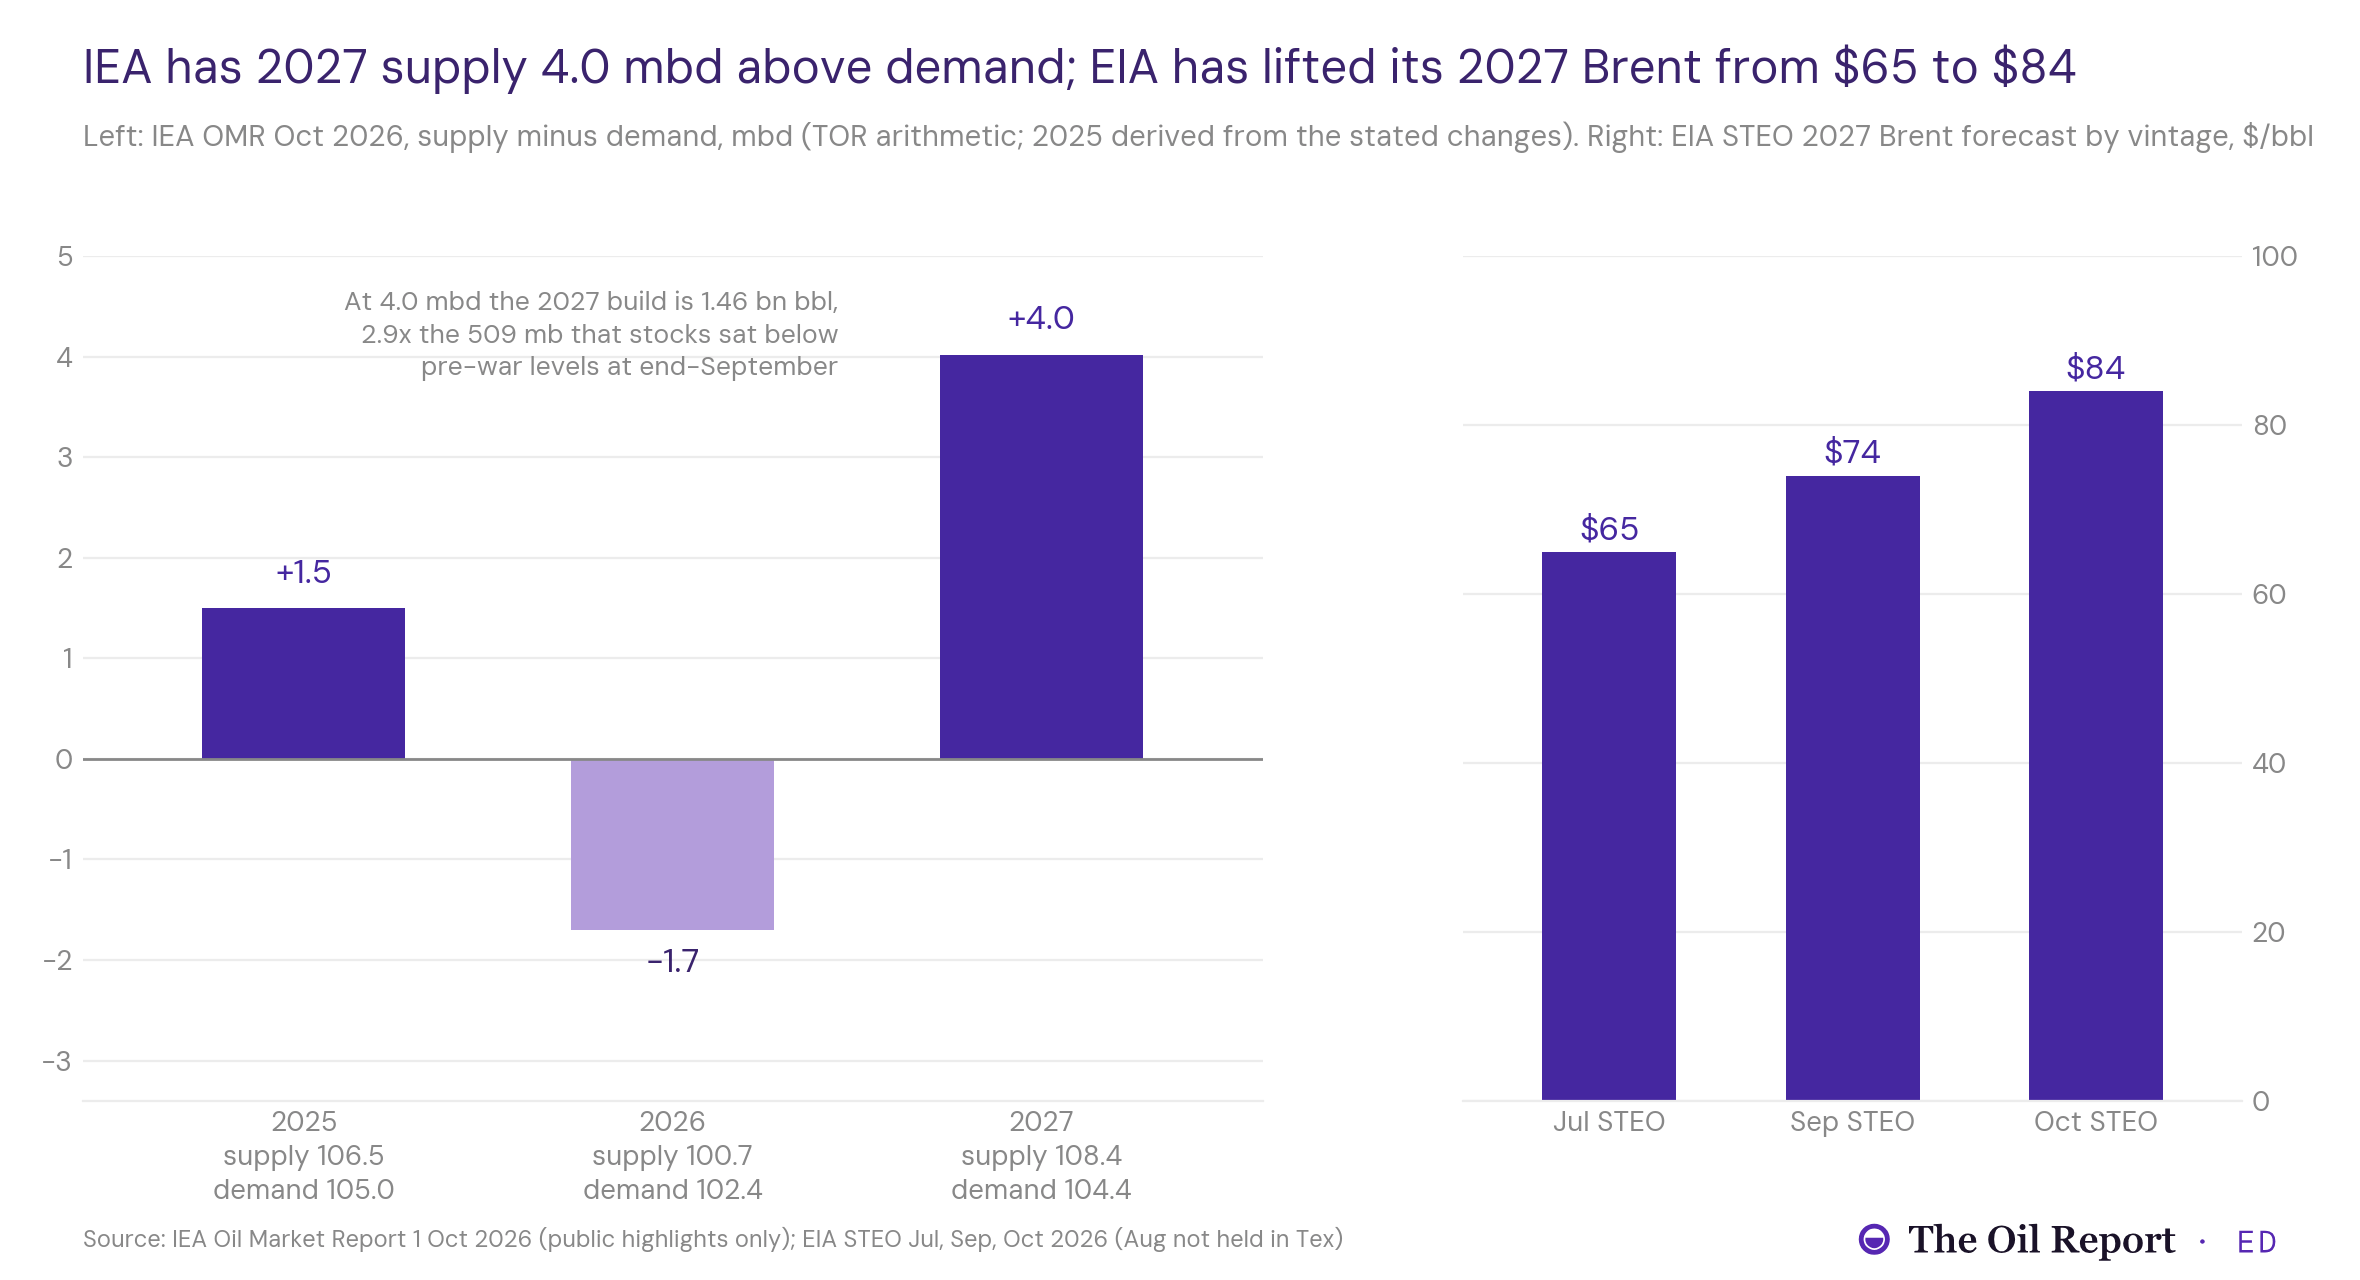
I’m going to cover calendar spreads to look at for this trade below and the macro thesis. The banks are wrong in the short term but right in the medium term. What is set to be higher forever now is products. With no new investments from oil majors going into refining. We will talk about this another day.
Fatigue. We are now at peak media fatigue on this war, giving way to the frenzy of US midterm elections which are leaning more and more blue. But I am staying in my lane. Let’s get a few key items out of the way from last week.
Tehran is taking meetings. Senior security officials from Saudi Arabia, Pakistan and Turkey, the members of the Mecca Joint Defence Agreement signed in August, met Iranian officials in Tehran on Monday (Euronews, Reuters, 26 Oct). On Tuesday Iran's Supreme Leader called for proposals setting out acceptable conditions to end the war, and crude dipped briefly (Newsquawk, 27 Oct). Nothing in the reporting gives terms.
Iran's Secretary of the Supreme National Security Council, Rezaei, told Pakistan's army chief that Iran rejects the American demands (Al Hadath, 21 Oct), and its Foreign Minister said on 21 Oct "we have not reached a state of peace and are far from it". The pact is also unproven, hence the flip-flop price action of last week: Houthi missile and drone attacks on Saudi Arabia are escalating, and Turkey has ruled out offensive operations against the Houthis (Euronews). As of today, Monday 2nd Nov, talks are ongoing with scant further details other than talks are quoted as ‘‘ongoing and progressing’’ -Iranian Foreign Minister Abbas Araqchi
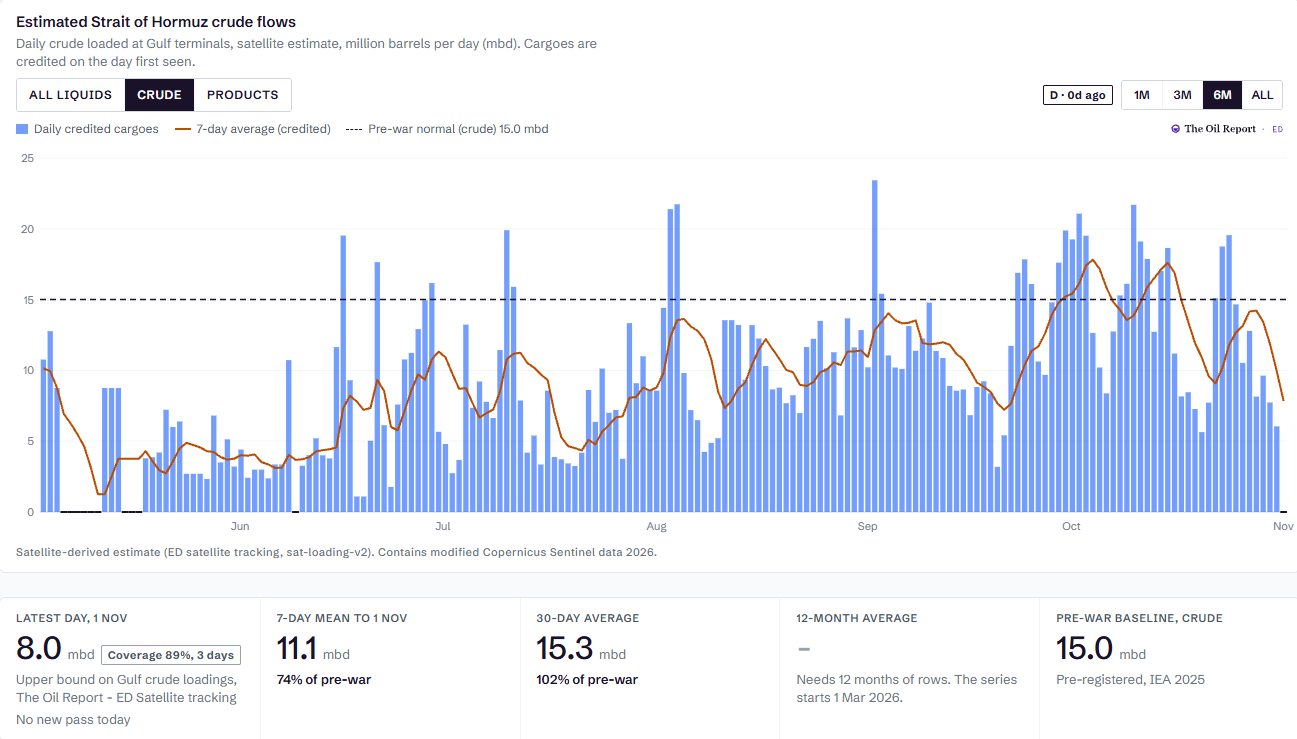
Ships are moving. US CENTCOM’s commander said the IRGC was not visible in the Strait of Hormuz when he transited earlier in the week. He said he saw dozens of commercial vessels, including cargo, crude, and LNG carriers, with US air and sea forces in place. CENTCOM says the US helped Gulf partners move over 1.5bln barrels of oil across the summer, and that Iran has been prevented from exporting oil (Newsquawk).
Now, 1.5bln barrels is a nice topline figure, but the market is firmly trading the ebb and flow of the straits. And we are firmly in an ebb right now. My system is Sentinel-1 and Sentinel-2 imagery with supportive data from 8 other satellites. So I am pretty confident in the latest numbers being within a 20% tolerance window. And I see flows averaging 11.1mb, with yesterday’s (Nov 1st) flows at 8mbd. Im happy to live with the tolerance window I have. I’m not trading physical.
Note on chart: my system is not yet splitting shipments by product. We have complex work ongoing internally to calculate this.
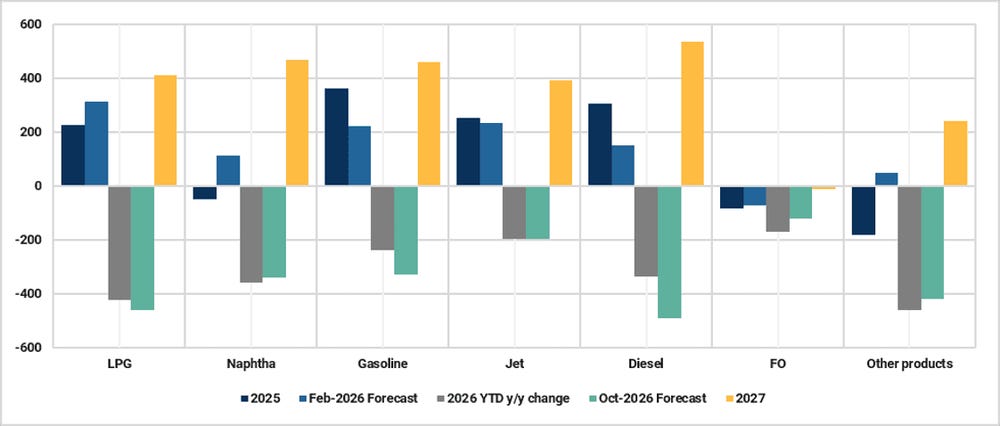
Demand is shrinking at the other end. Kpler puts refined products demand down 2.4 mbd in 2026, concentrated in the second and third quarters, with gasoil and diesel hardest hit at 500 kbd (Europe -280 kbd, China -200 kbd), then LPG at 460 kbd and naphtha at 350 kbd. This really has to be studied now as traditional ‘price led’ demand destruction. Supply constraints initially, coupled with refining utilisation constraints, led to higher product prices, then bamo, demand drops. Moving to the new energy blocks of electrons not molecules.
Kpler and IEA expect an uneven rebound of about 2.5 mbd in 2027, with Chinese EVs and LNG trucks capping road fuels.
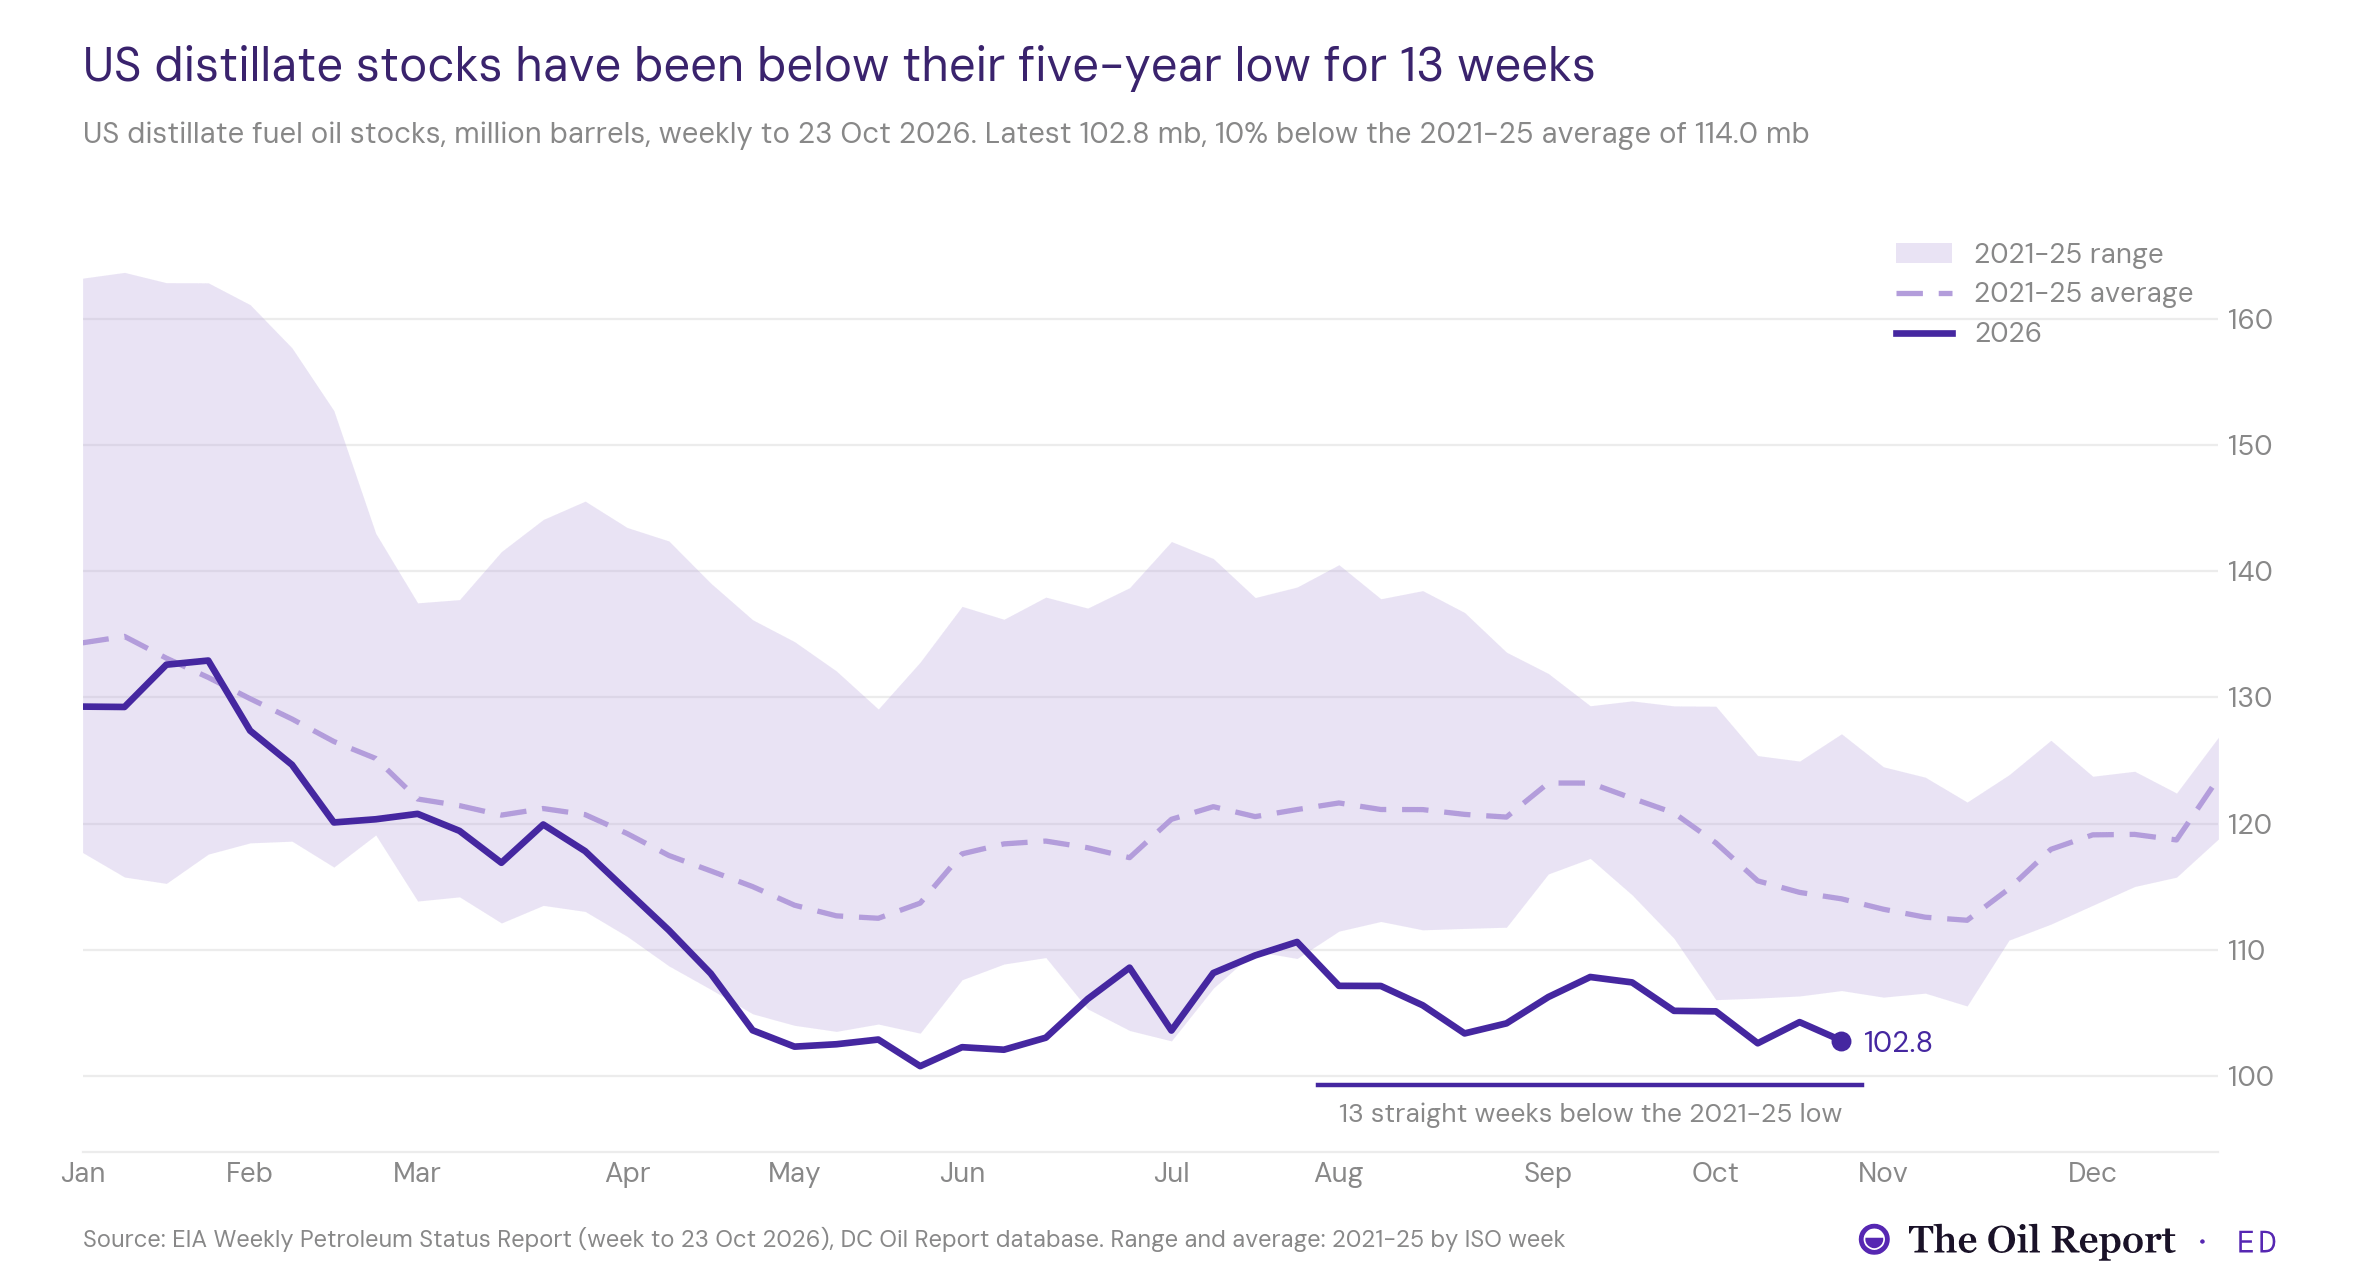
US diesel has no spare cushion. Like we didn’t know. But I think it’s important to mark where we are here as we close out the harvesting season in the Northern Hemisphere. I expect that inventories have made it through the largest near point demand. I expect to monitor builds from here through to end of winter. Stay tuned to the weekly EIA report I release.
Distillate stocks fell 1.5 mb to 102.8 mb in the week to 23 Oct, 10% under the 2021-25 average for the week (114.1 mb) and below the 2021-25 low (106.8 mb) for 13 straight weeks. Refinery utilisation was 92.8% (EIA WPSR). Diesel is where the demand loss and the stock shortage meet: Kpler has it as the biggest 2026 demand cut, and US stocks sit under the 2021-25 low.
Whether Brent holds below April's high depends on whether any of the talk in Tehran changes the barrels leaving the Gulf. For now, it is actually having a negative effect.
Structural bid - the details